Turning Financial Insights Into Better Spending Decisions
Designing a guidance-driven expense-management experience that helps users understand and control their spending.
- Role
- UI/UX Designer
- Responsibilities
- Research, product direction, user flows, visual design, and prototyping
- Primary user
- People managing everyday expenses
- Outcome
- Expected better financial savings
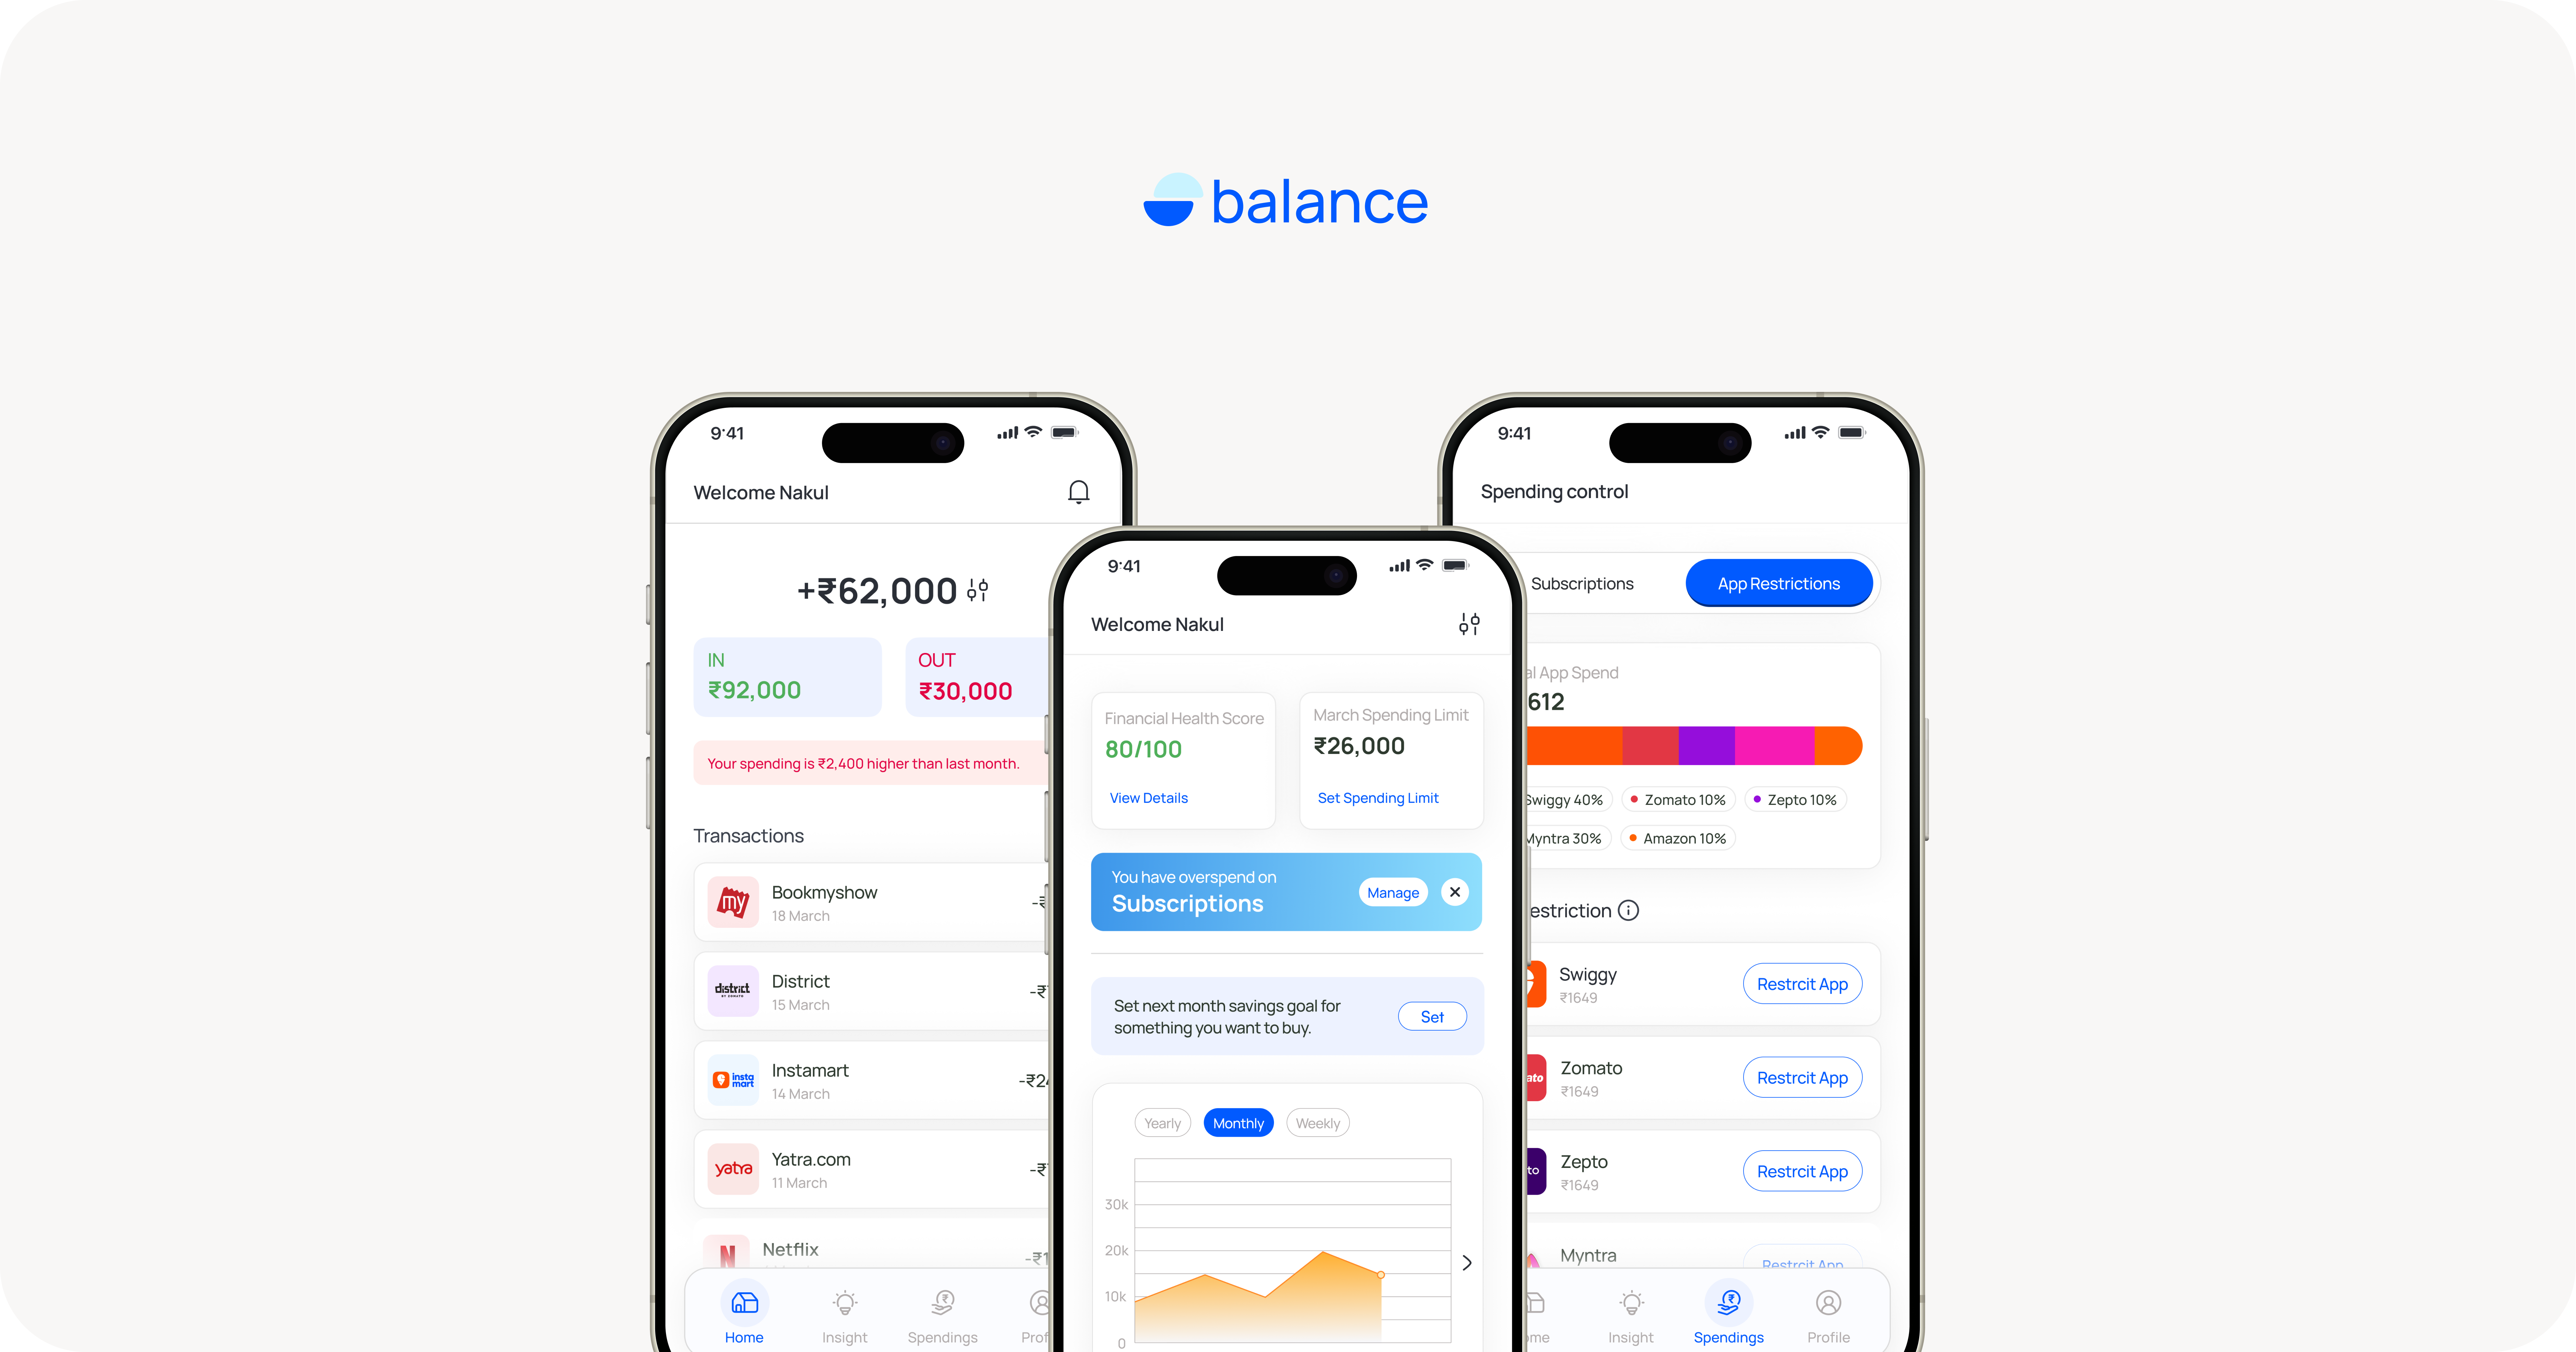
Problem I faced
I have faced difficulties in managing my finances in a better way although I have used enough apps for managing my finances. While some apps helped me in tracking transactions and monitoring my spending, they rarely helped me in controlling my spending in an efficient way.
So I decided to take the problem into my hands and explore how a better expense-management experience could be designed.
Instead of taking the old route of wireframing and iterations, I decided to make things faster with the help of Figma Make AI.
Research / Assumptions
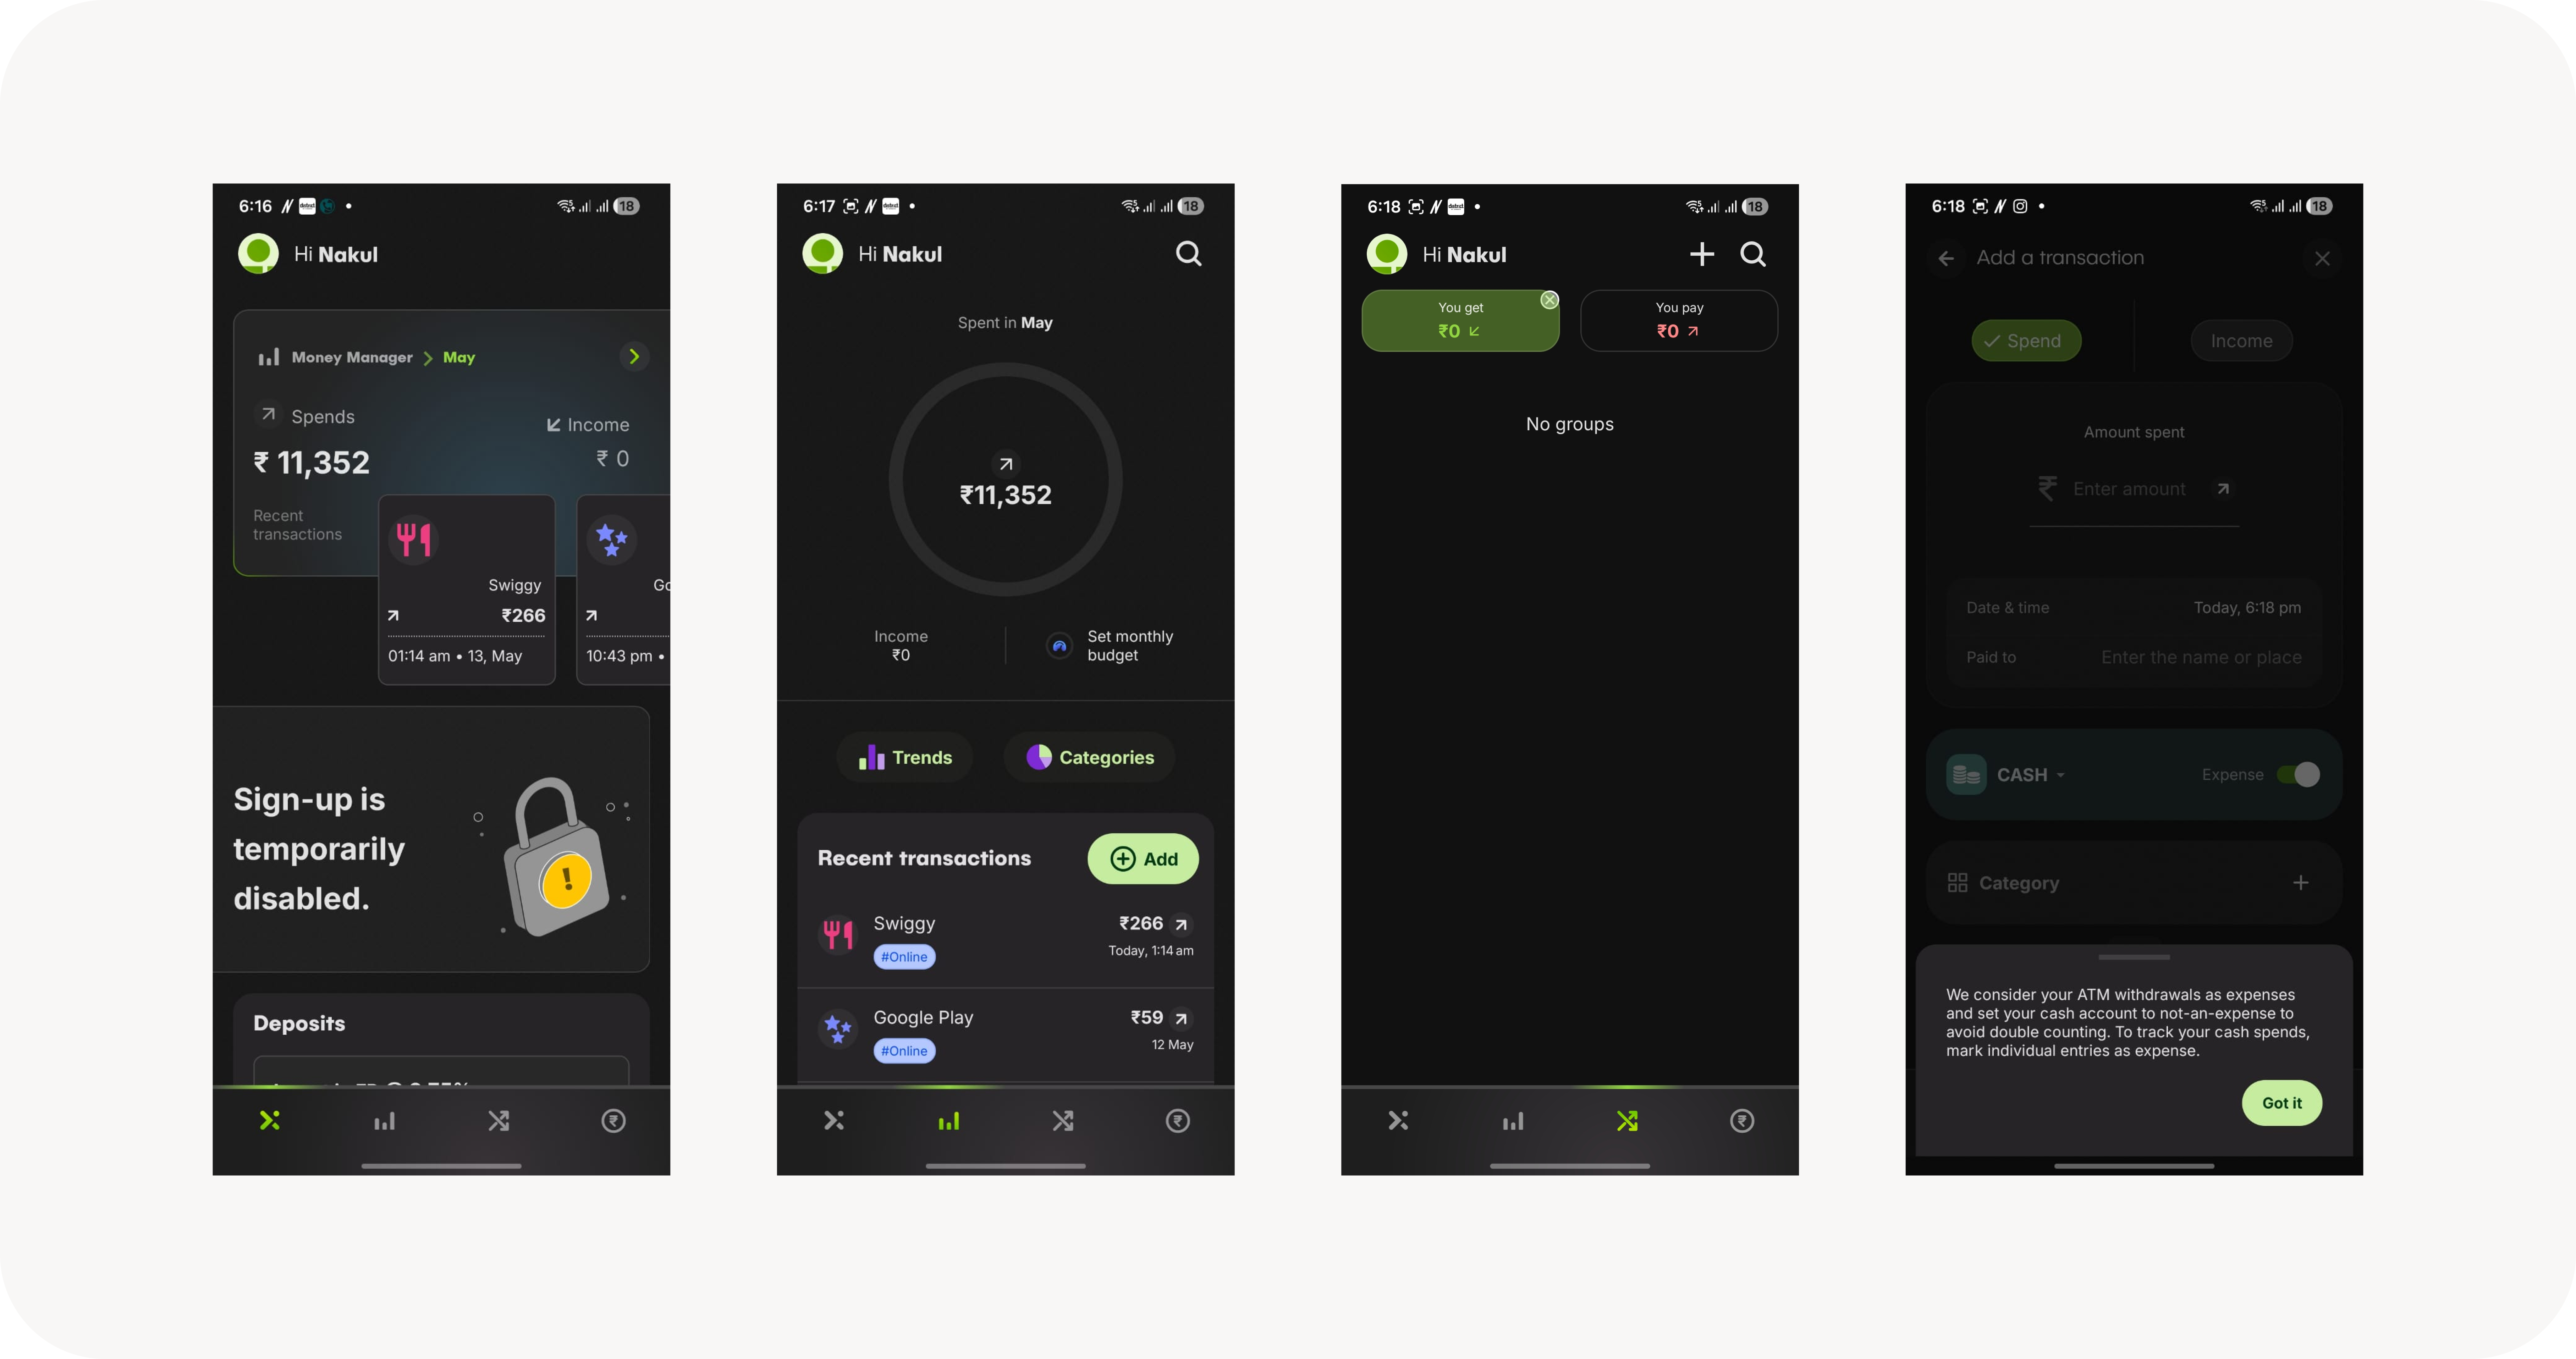
I’ve spent a lot of time exploring various personal finance apps, and Axio stood out as a good app.
Although it is a fantastic app for tracking transactions and monitoring where money goes, it lacks any real proactive spending control.
What Was Lacking in the Existing Applications?
- For a user without financial knowledge, the app can feel data-heavy rather than guidance-driven. It shows what users spend on, but not why their spending habits matter or how they could improve them.
- Another missing element was actual spending control. The app tracked expenses well, but did not guide users with actions or suggestions that could help them reduce overspending or build better financial habits.
Assumptions
- A major part of small unnecessary spending is on food delivery, subscriptions, and online shopping.
- It is hard to track and manage subscriptions when they are high in volume.
Food Delivery
AI made my research easier. Here are some food-delivery insights:
- Average monthly spending on online food delivery is growing in Tier-1 cities.
- Tier-1 cities contribute roughly 75–80% of the total market value, which is why I focused on Tier-1 city data.
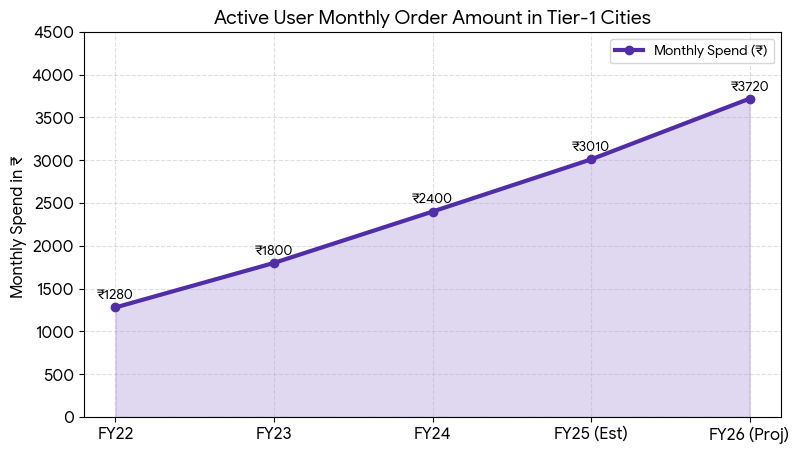
Some interesting insights I found:
- The “Power User” peak: top-tier users, such as tech professionals in Bengaluru, have been reported spending as much as ₹35,000 per month on delivery apps.
- The Indian online food-delivery sector is projected to maintain a strong CAGR of 17–23% through 2030.
Subscriptions:
The growing number of OTT platforms and increased use of AI tools make subscriptions difficult for users to manage.
The Tier-1 subscription count:
- The working professional—6 to 8 active subscriptions: common for someone balancing work, fitness, and home management.
- The “Power User” / tech-native—10 to 14 active subscriptions: common among Gen Z and tech professionals paying for multiple AI tools and niche productivity apps.
Exploration / Product Direction
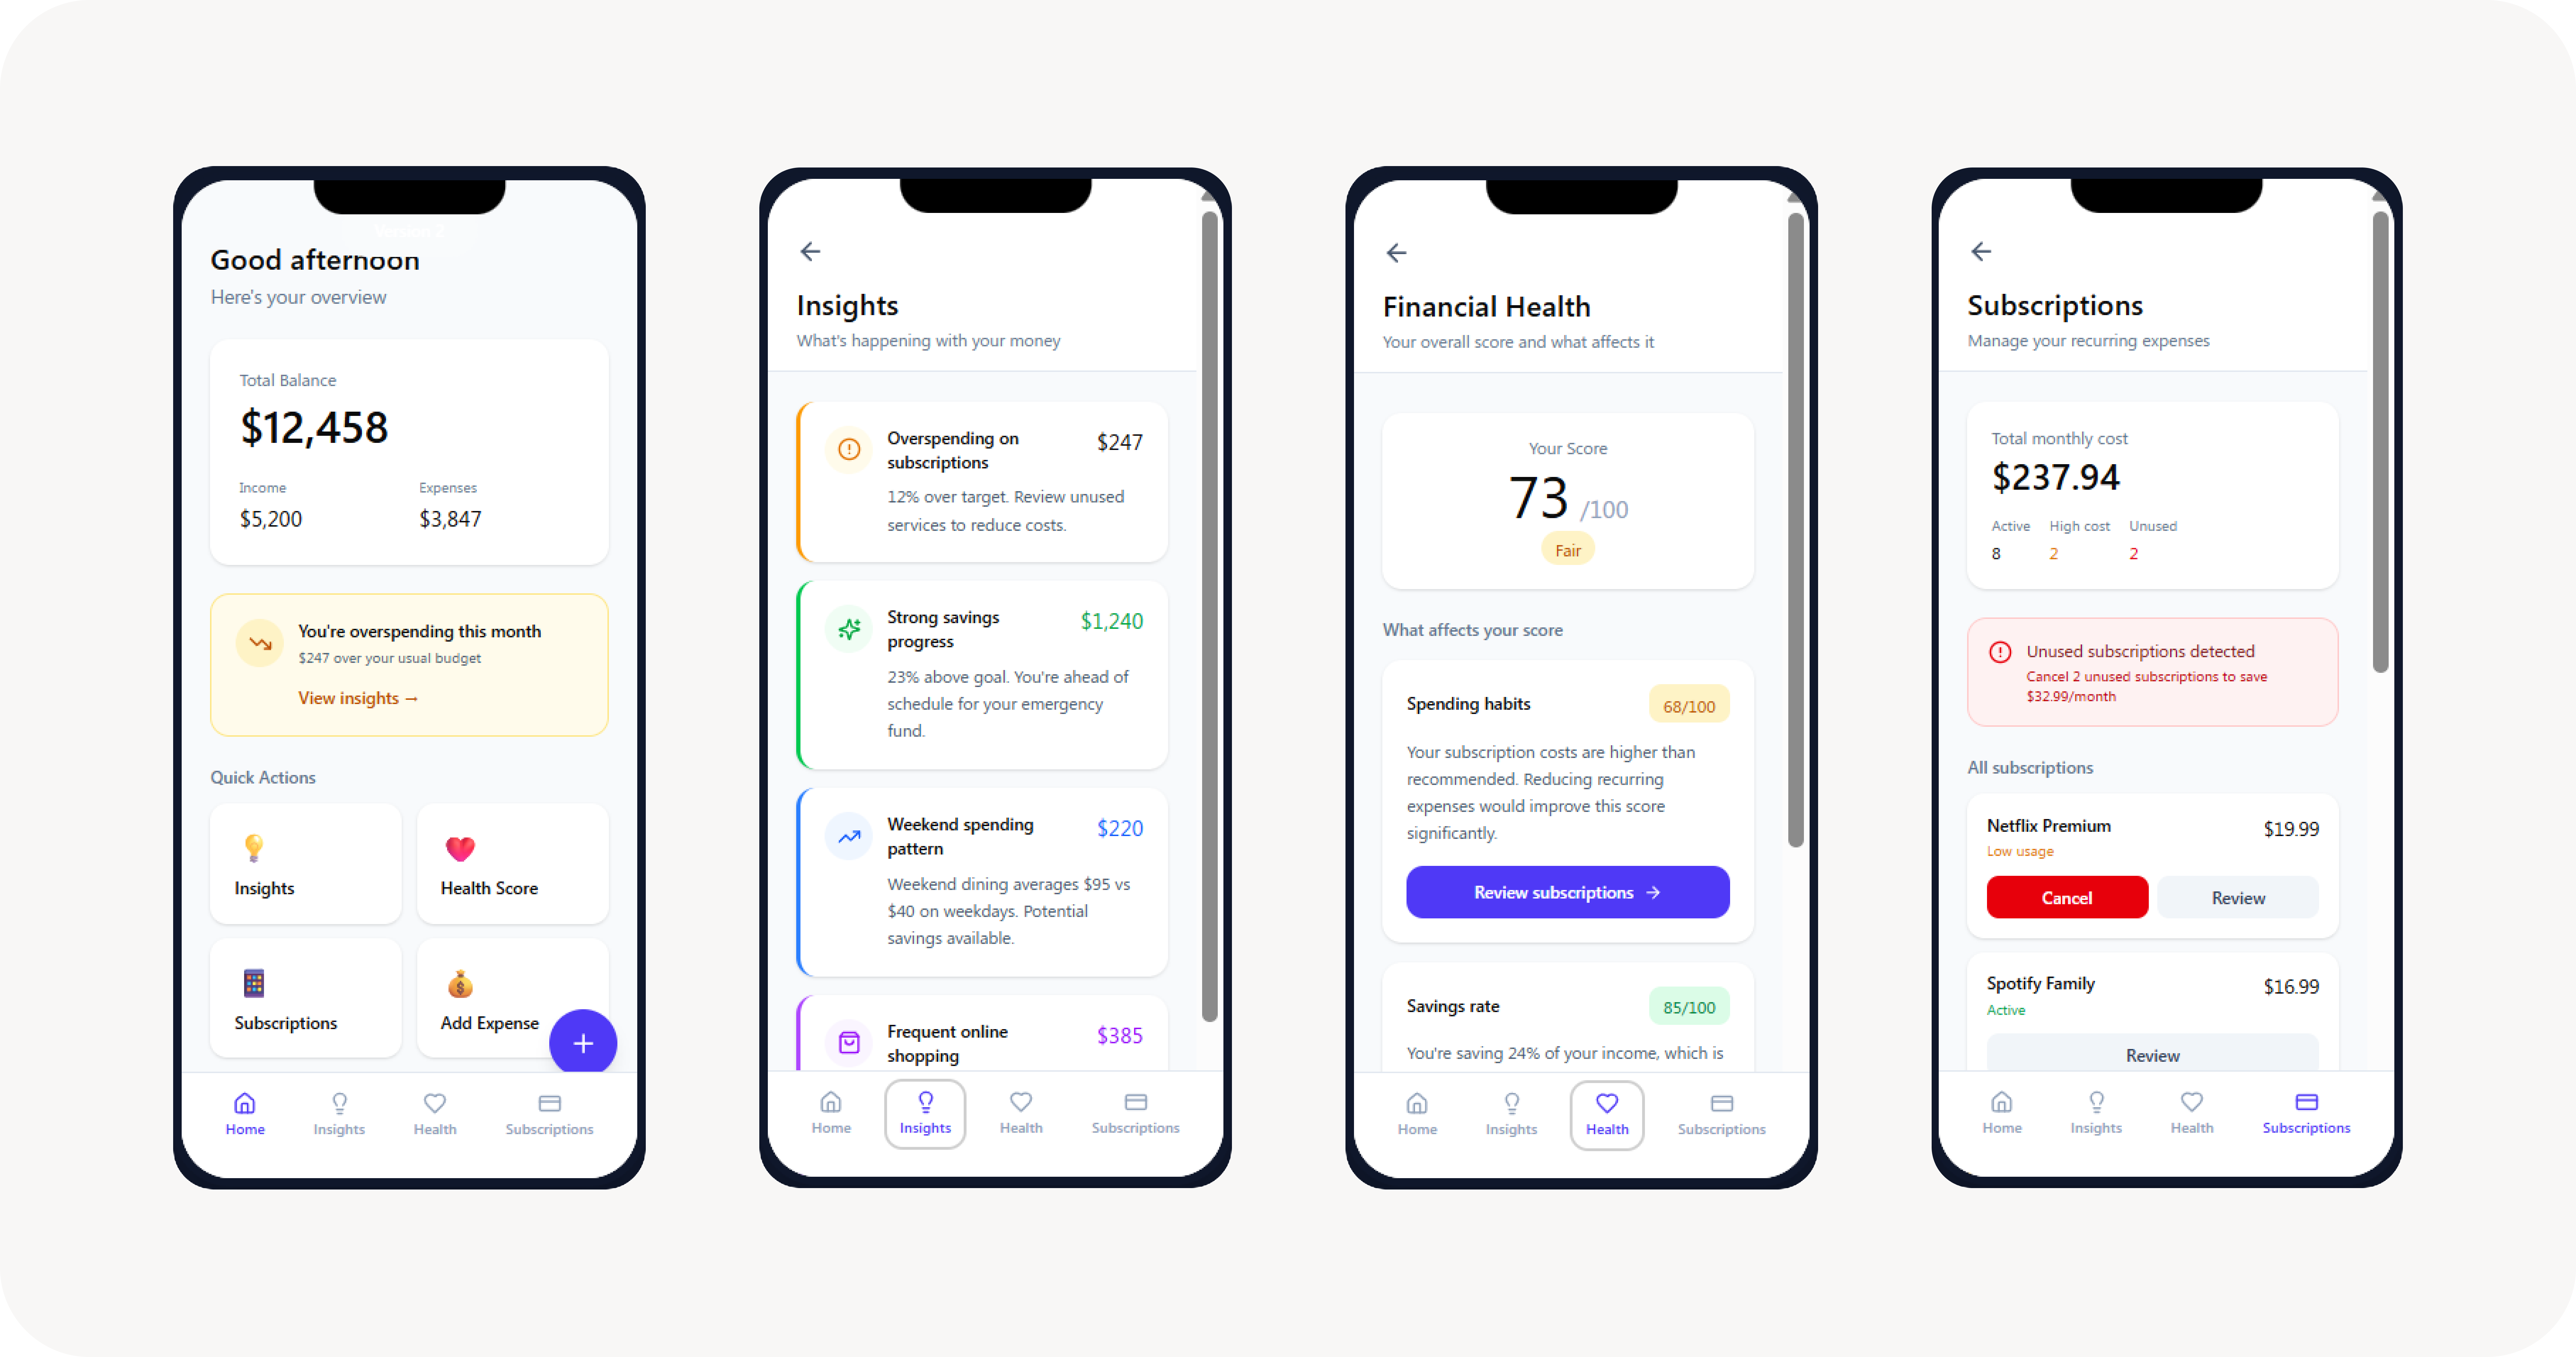
During the early exploration phase, while thinking about ideas for the app, I used Figma Make to quickly develop early ideas and layouts.
Even though the Figma Make designs were not close to the final direction I had in mind, they still provided inspiration and helped me understand the basic structure of the app.
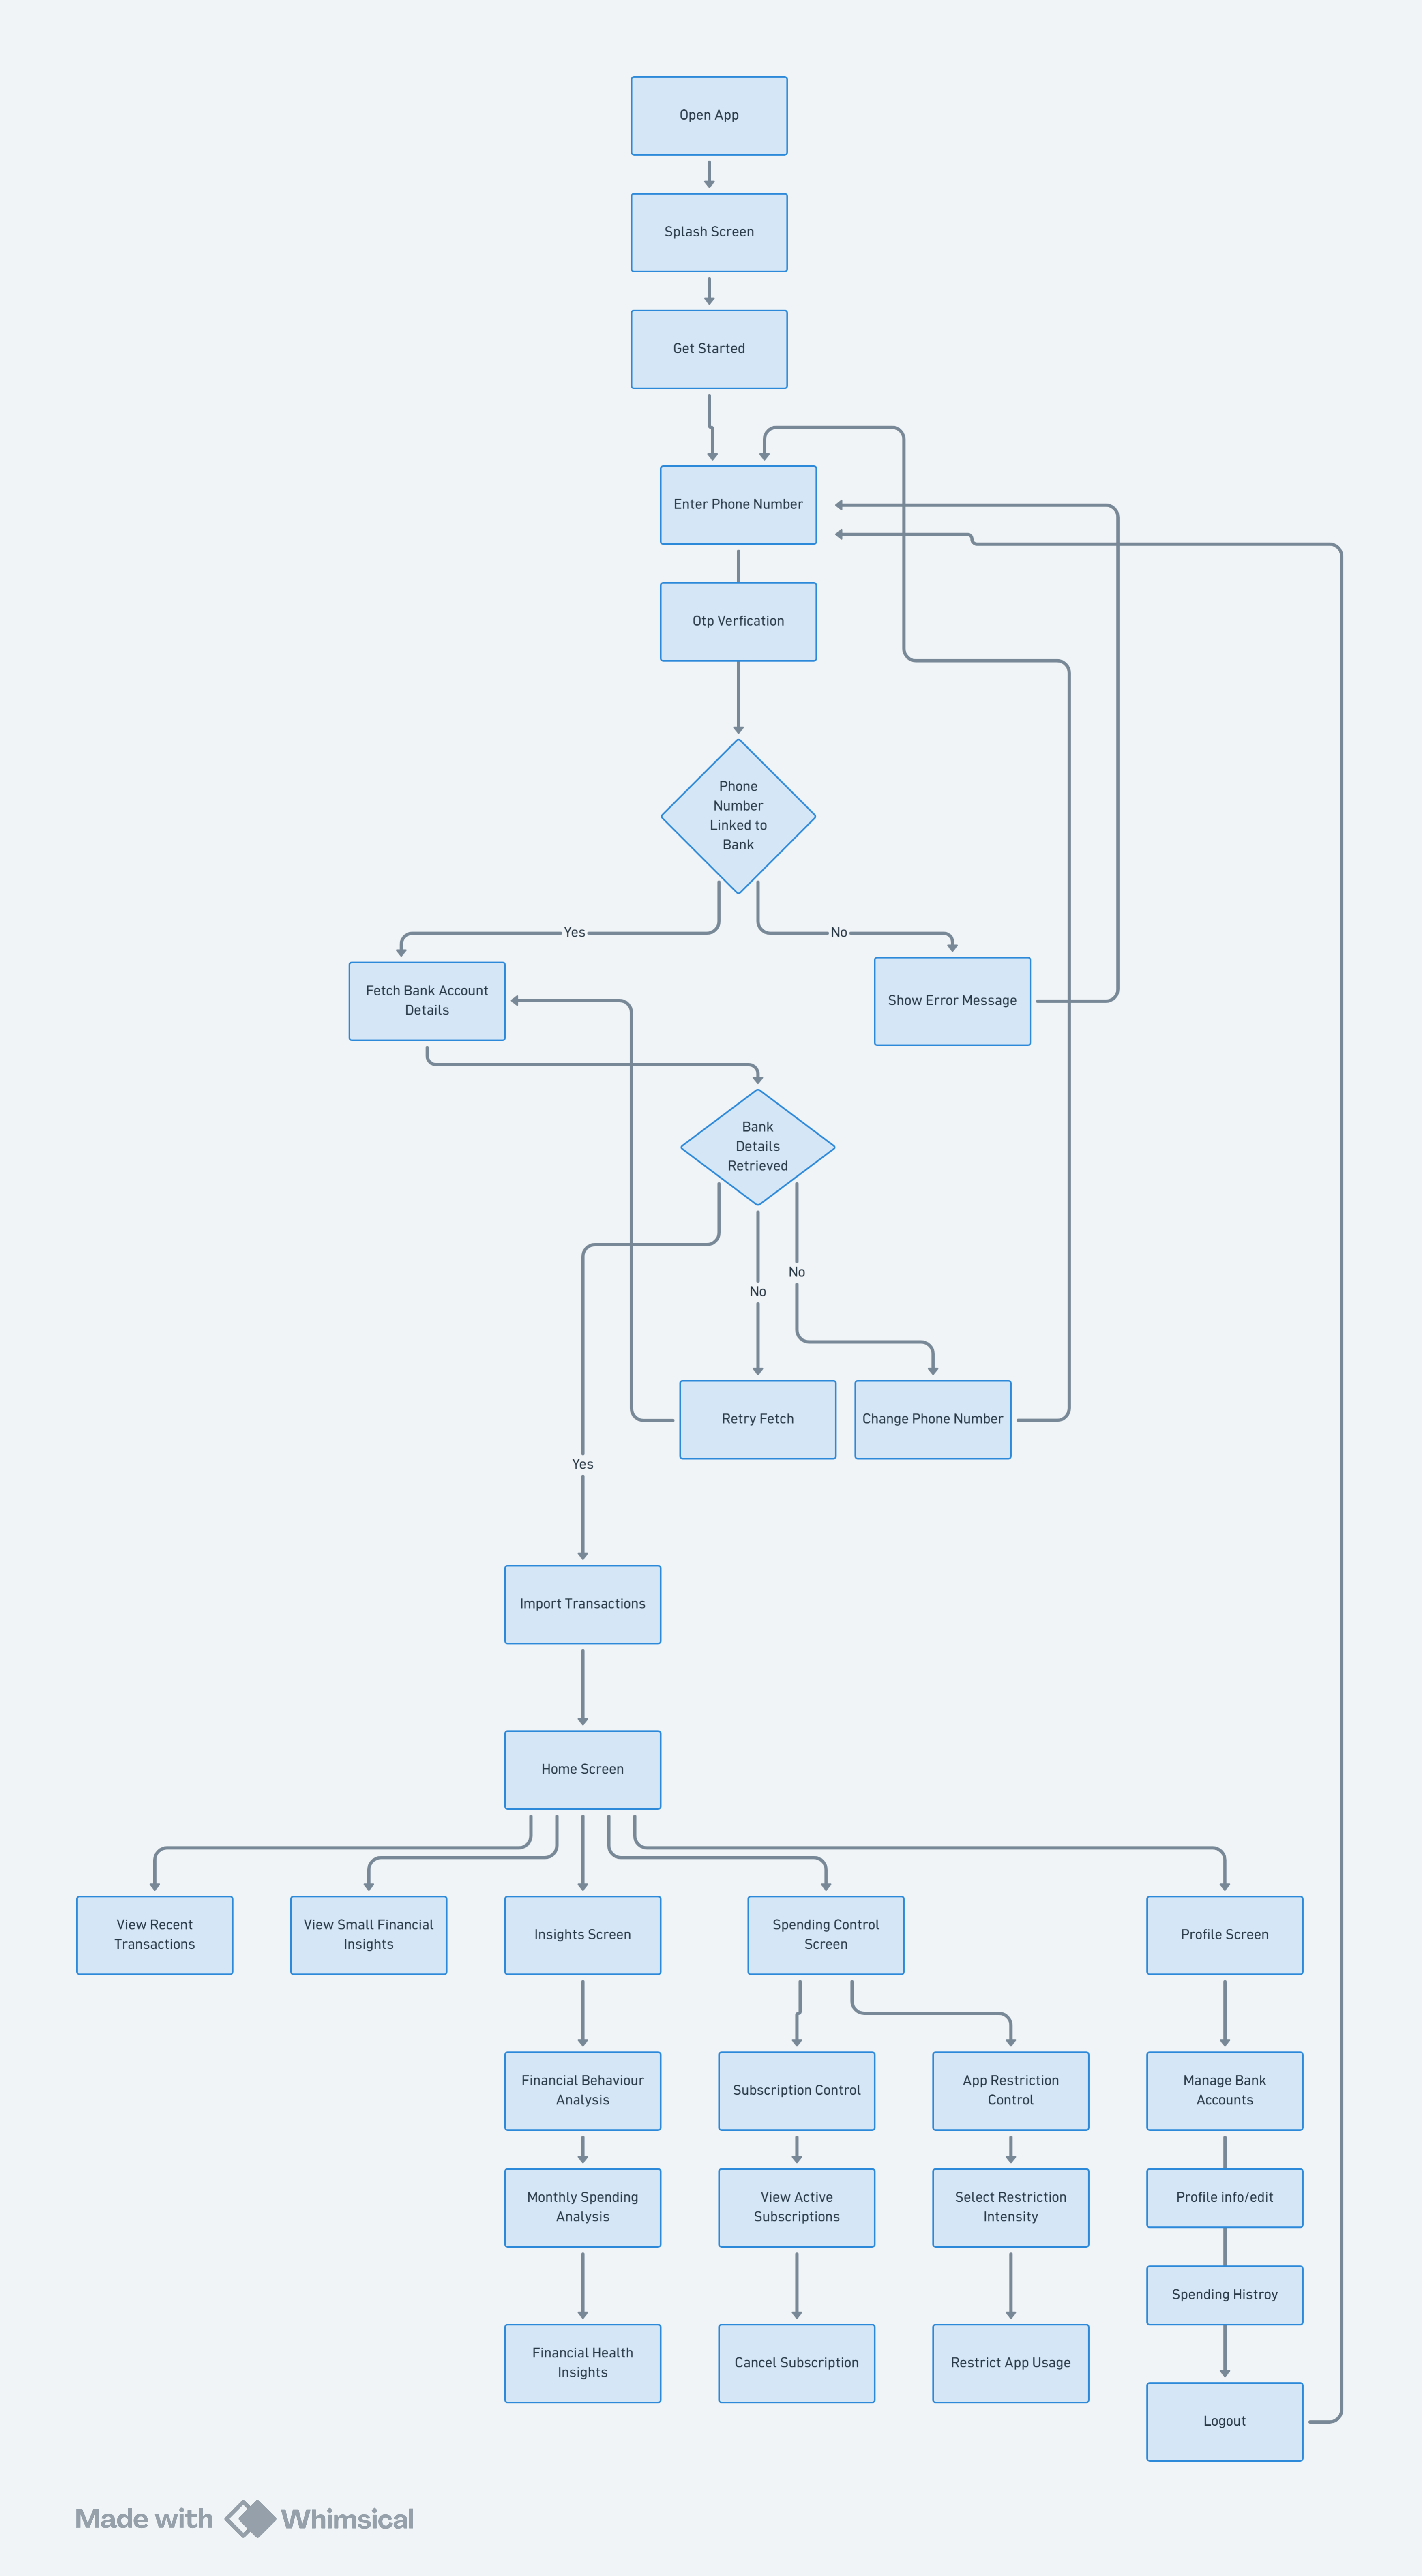
Behavioral Flow

UI Designs / Design Decisions
I divided the whole app into three parts that I believe—and also found in my research—are most necessary:
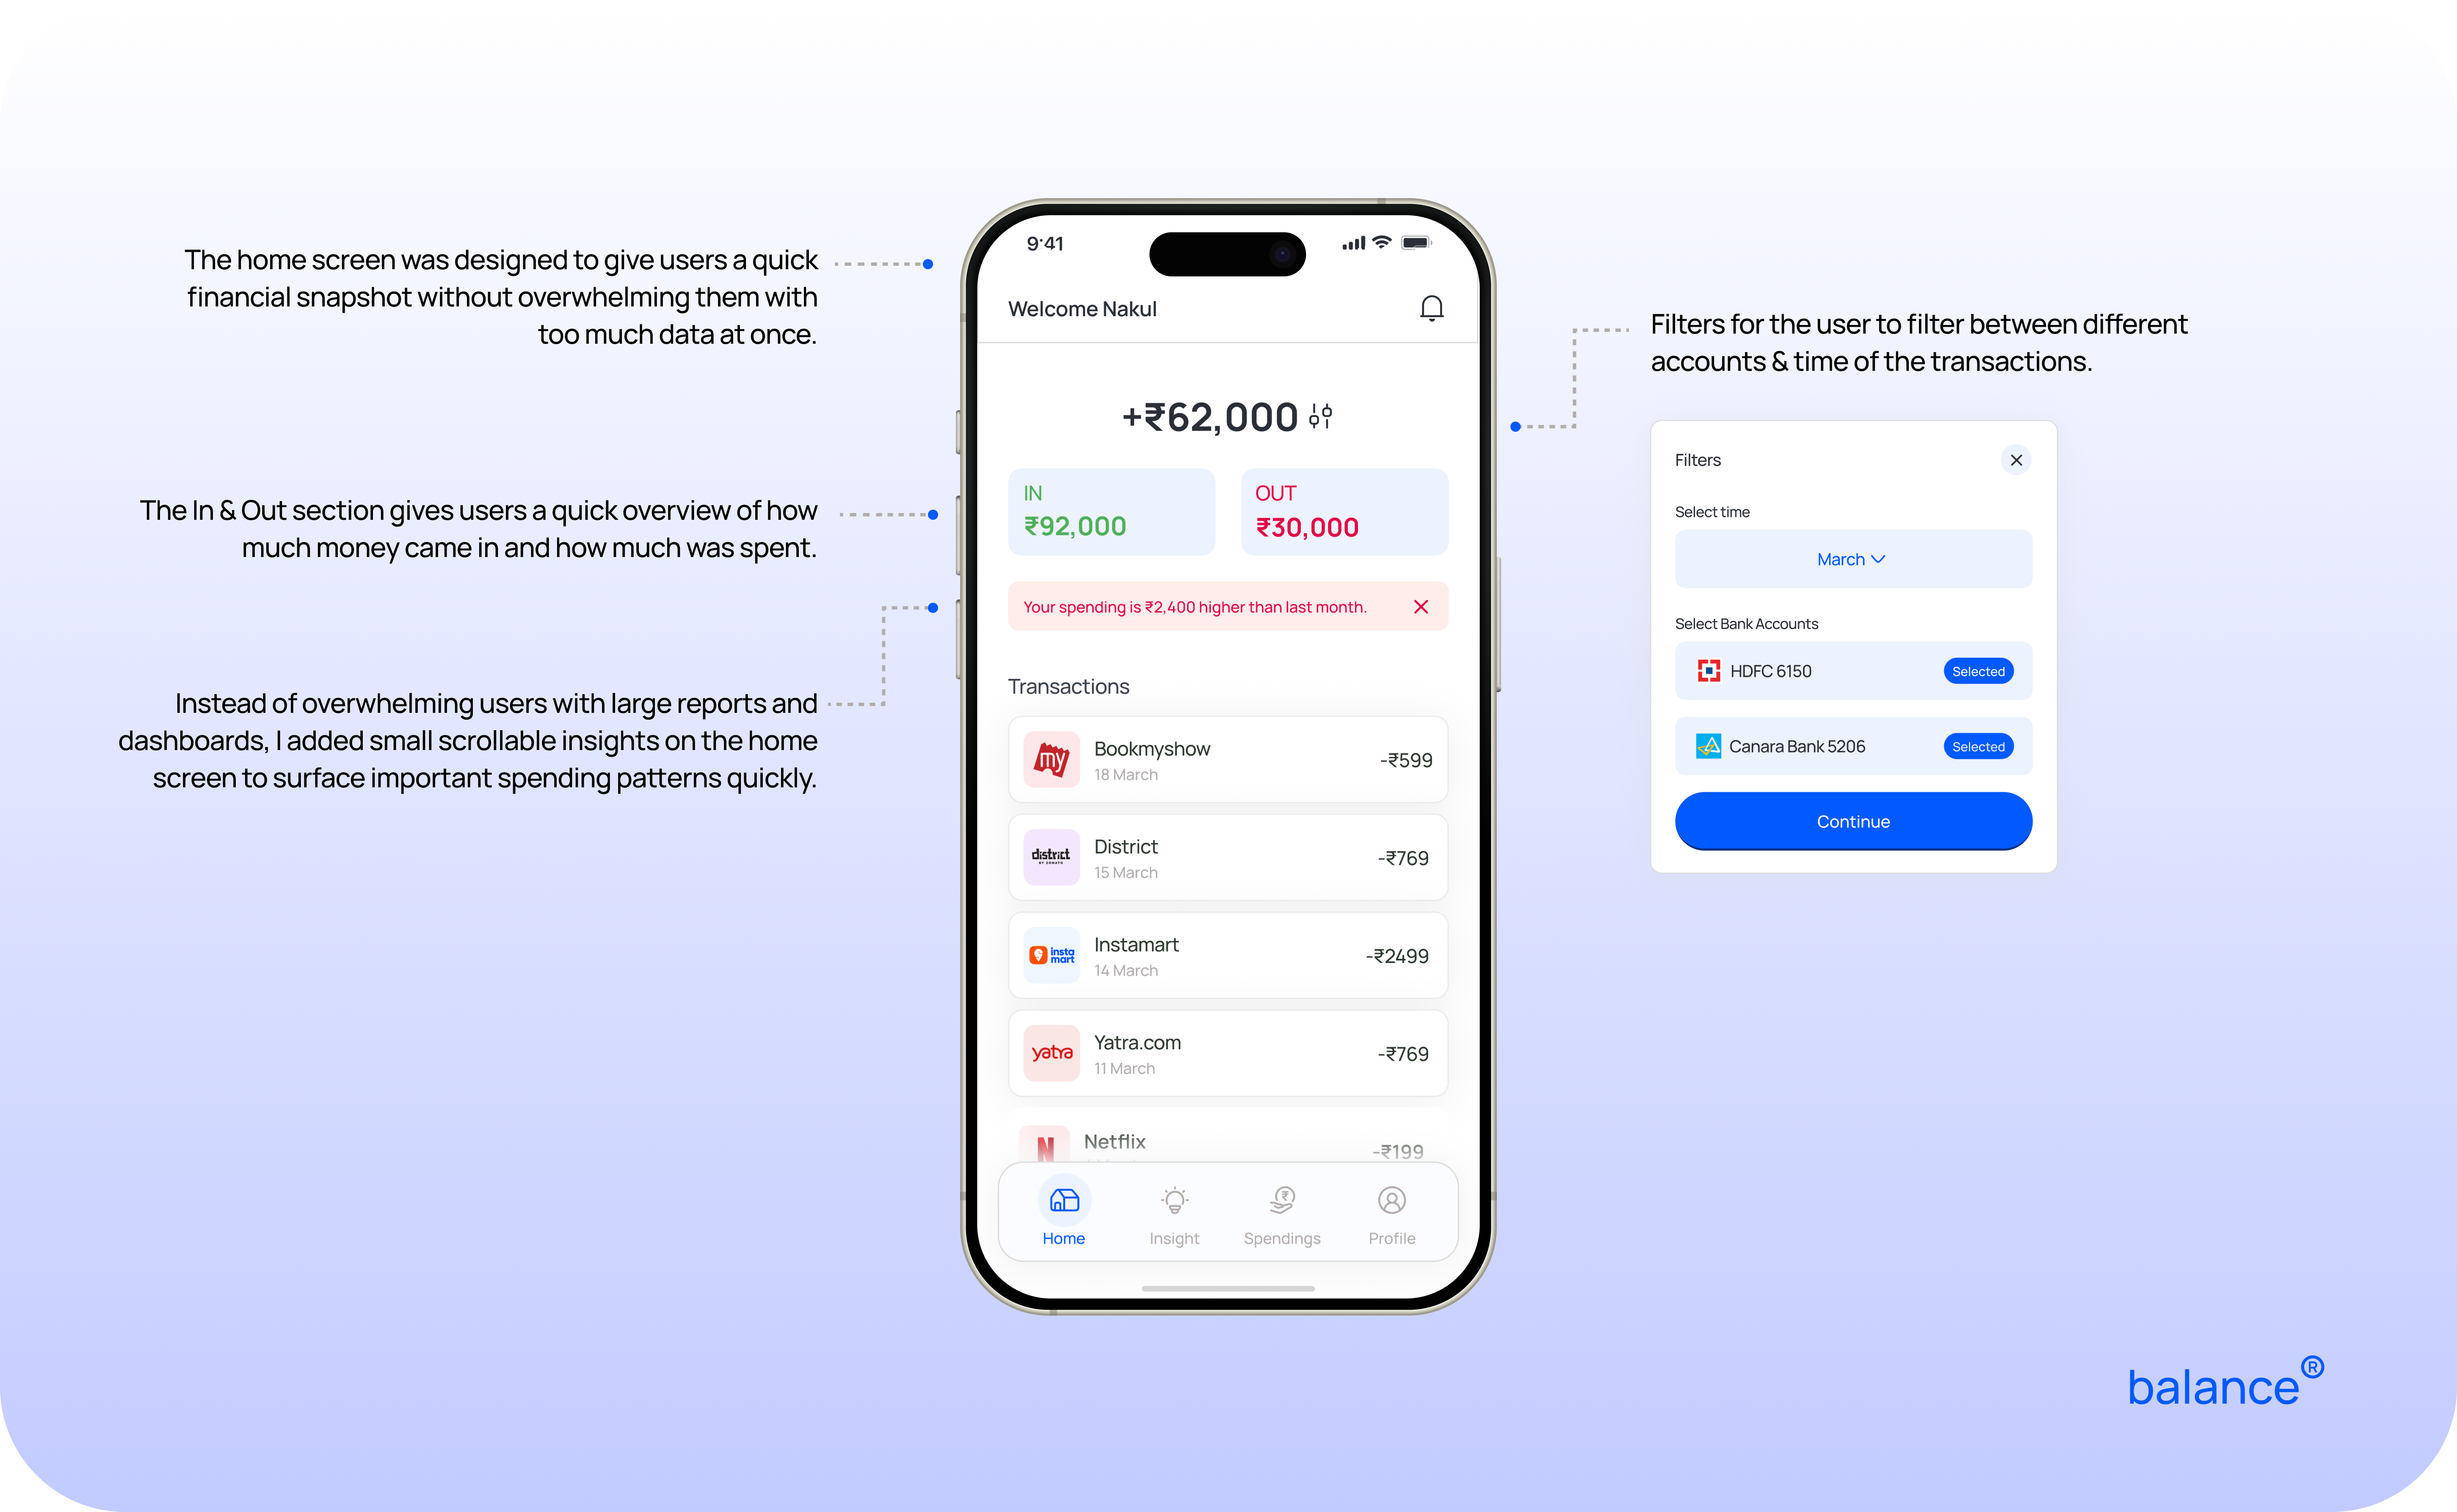
- Transactions—This area focuses on everything related to transactions. Instead of overwhelming users with too much data, I kept it simple by showing spending, income, and recent transactions in a clean and easy-to-understand way.
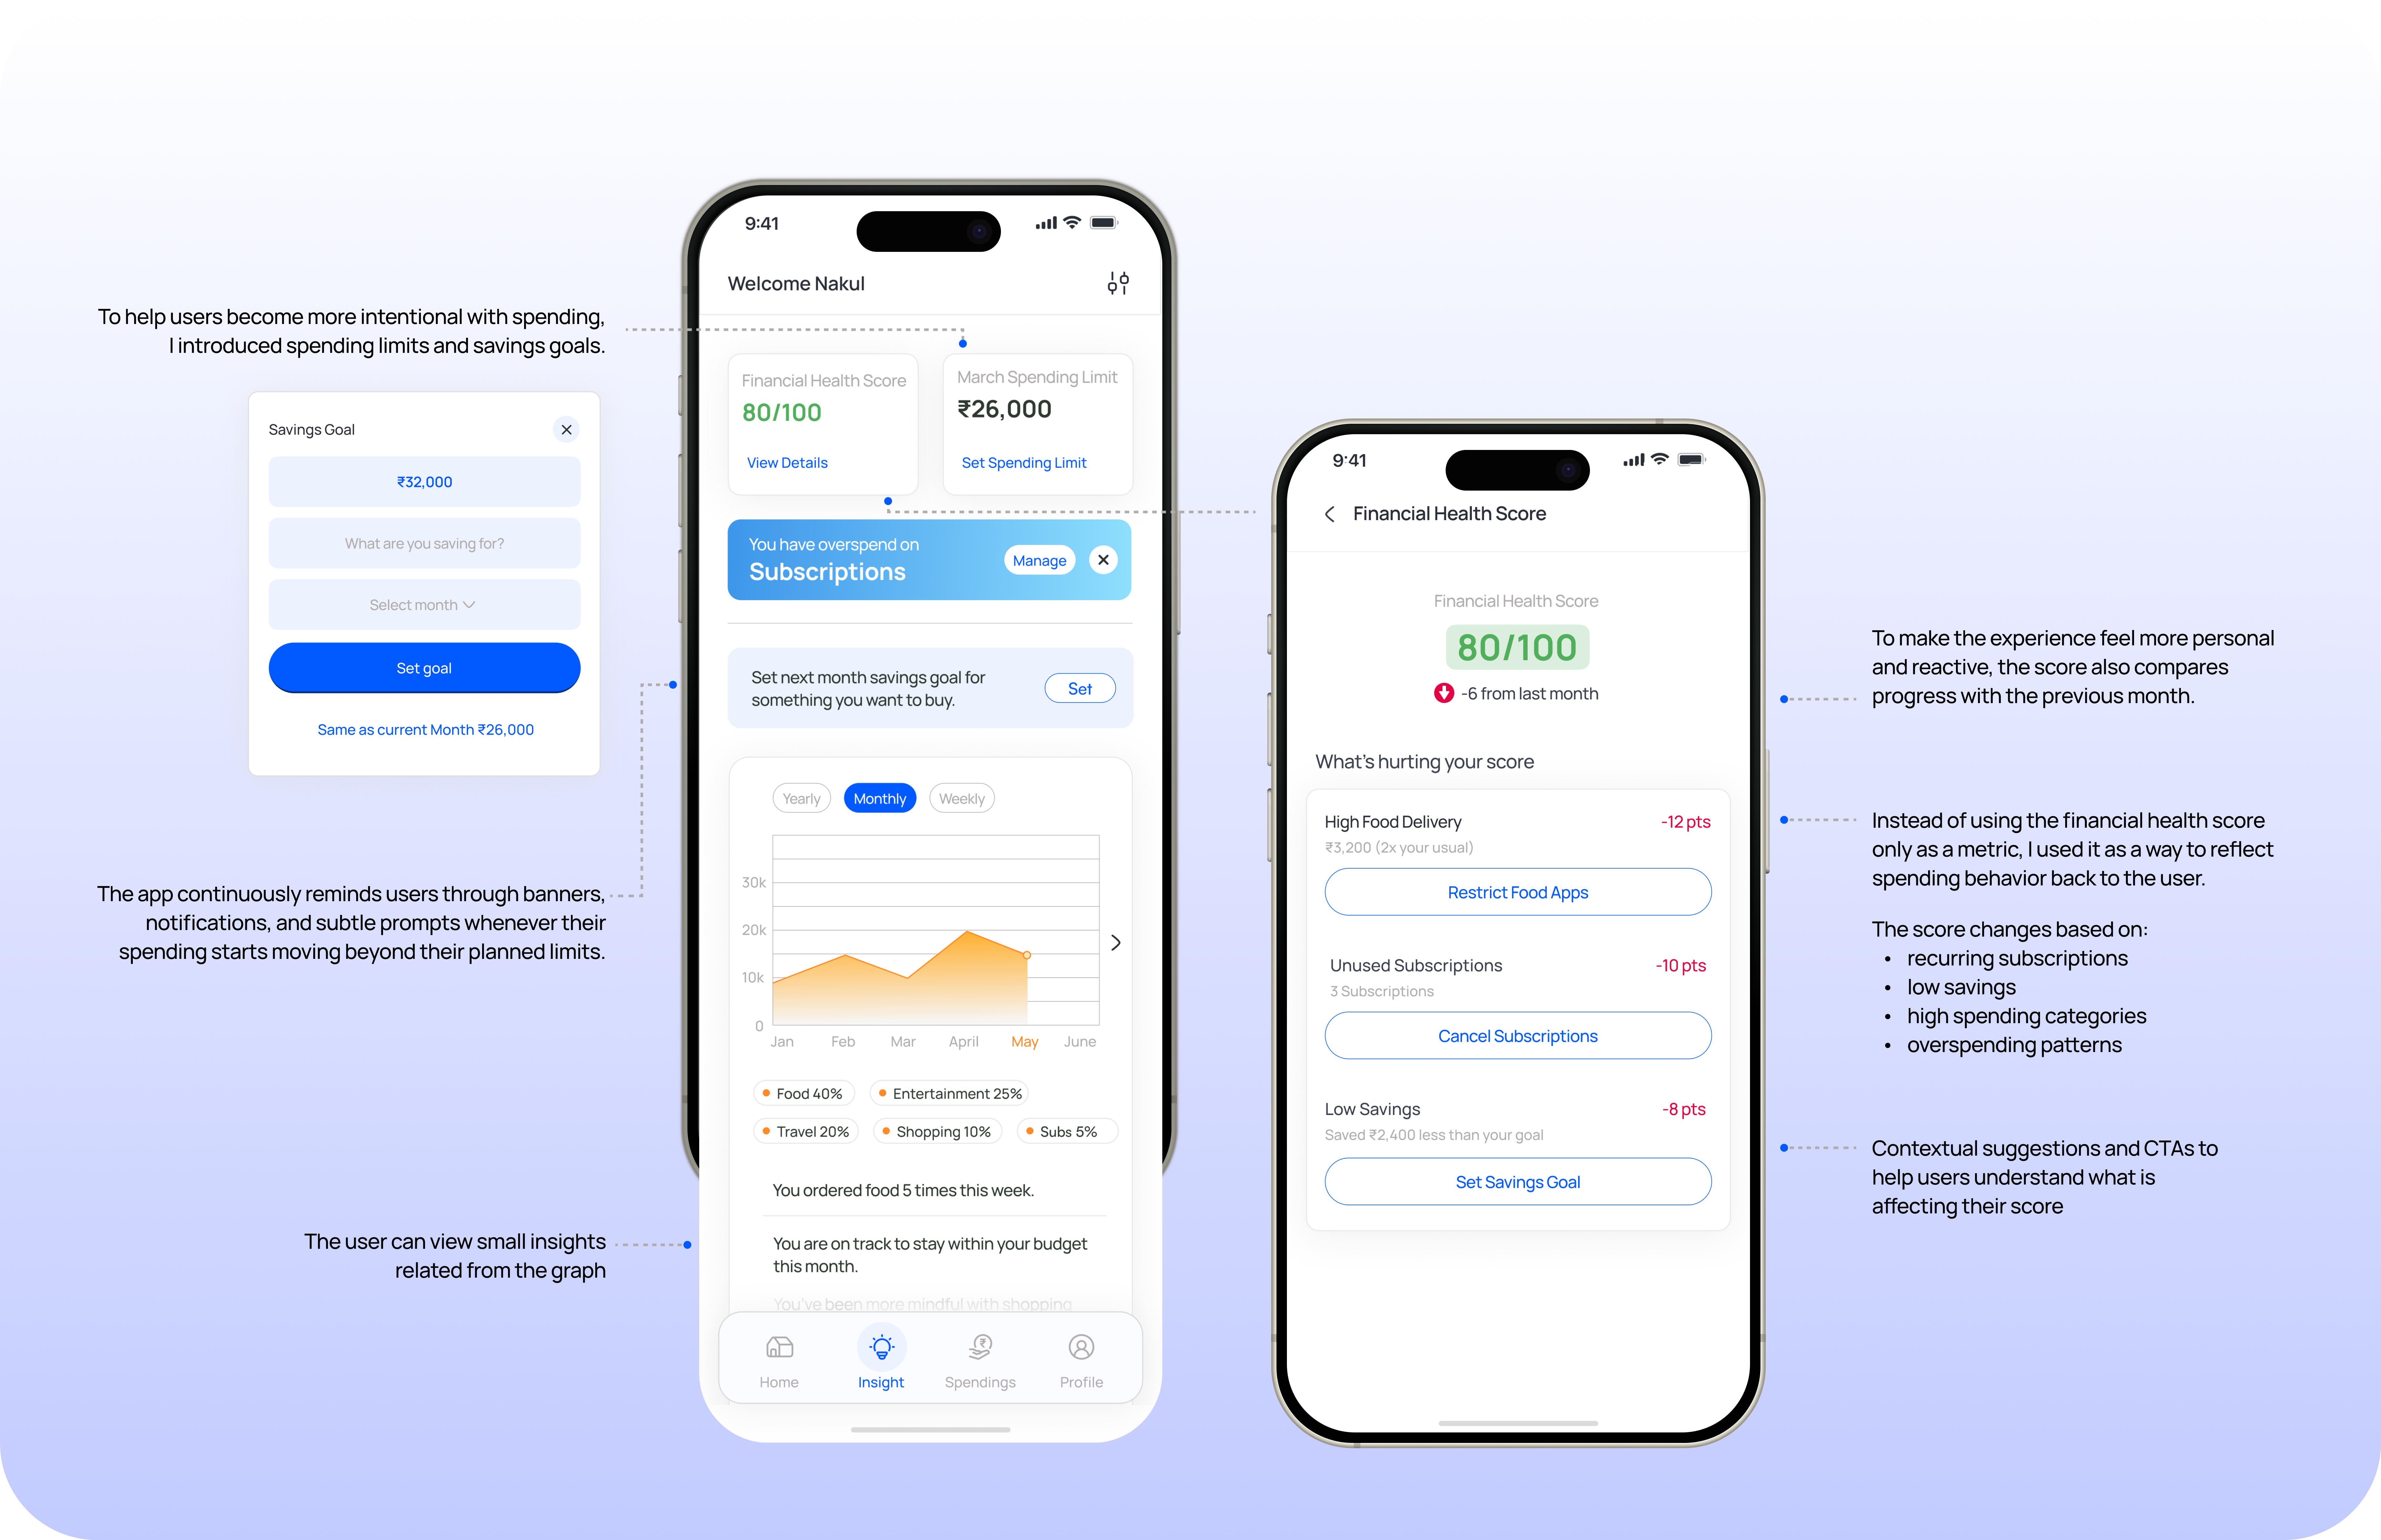
- Insights—This section helps users understand their spending habits through simple insights related to subscriptions, food delivery, entertainment, shopping, and other recurring patterns.
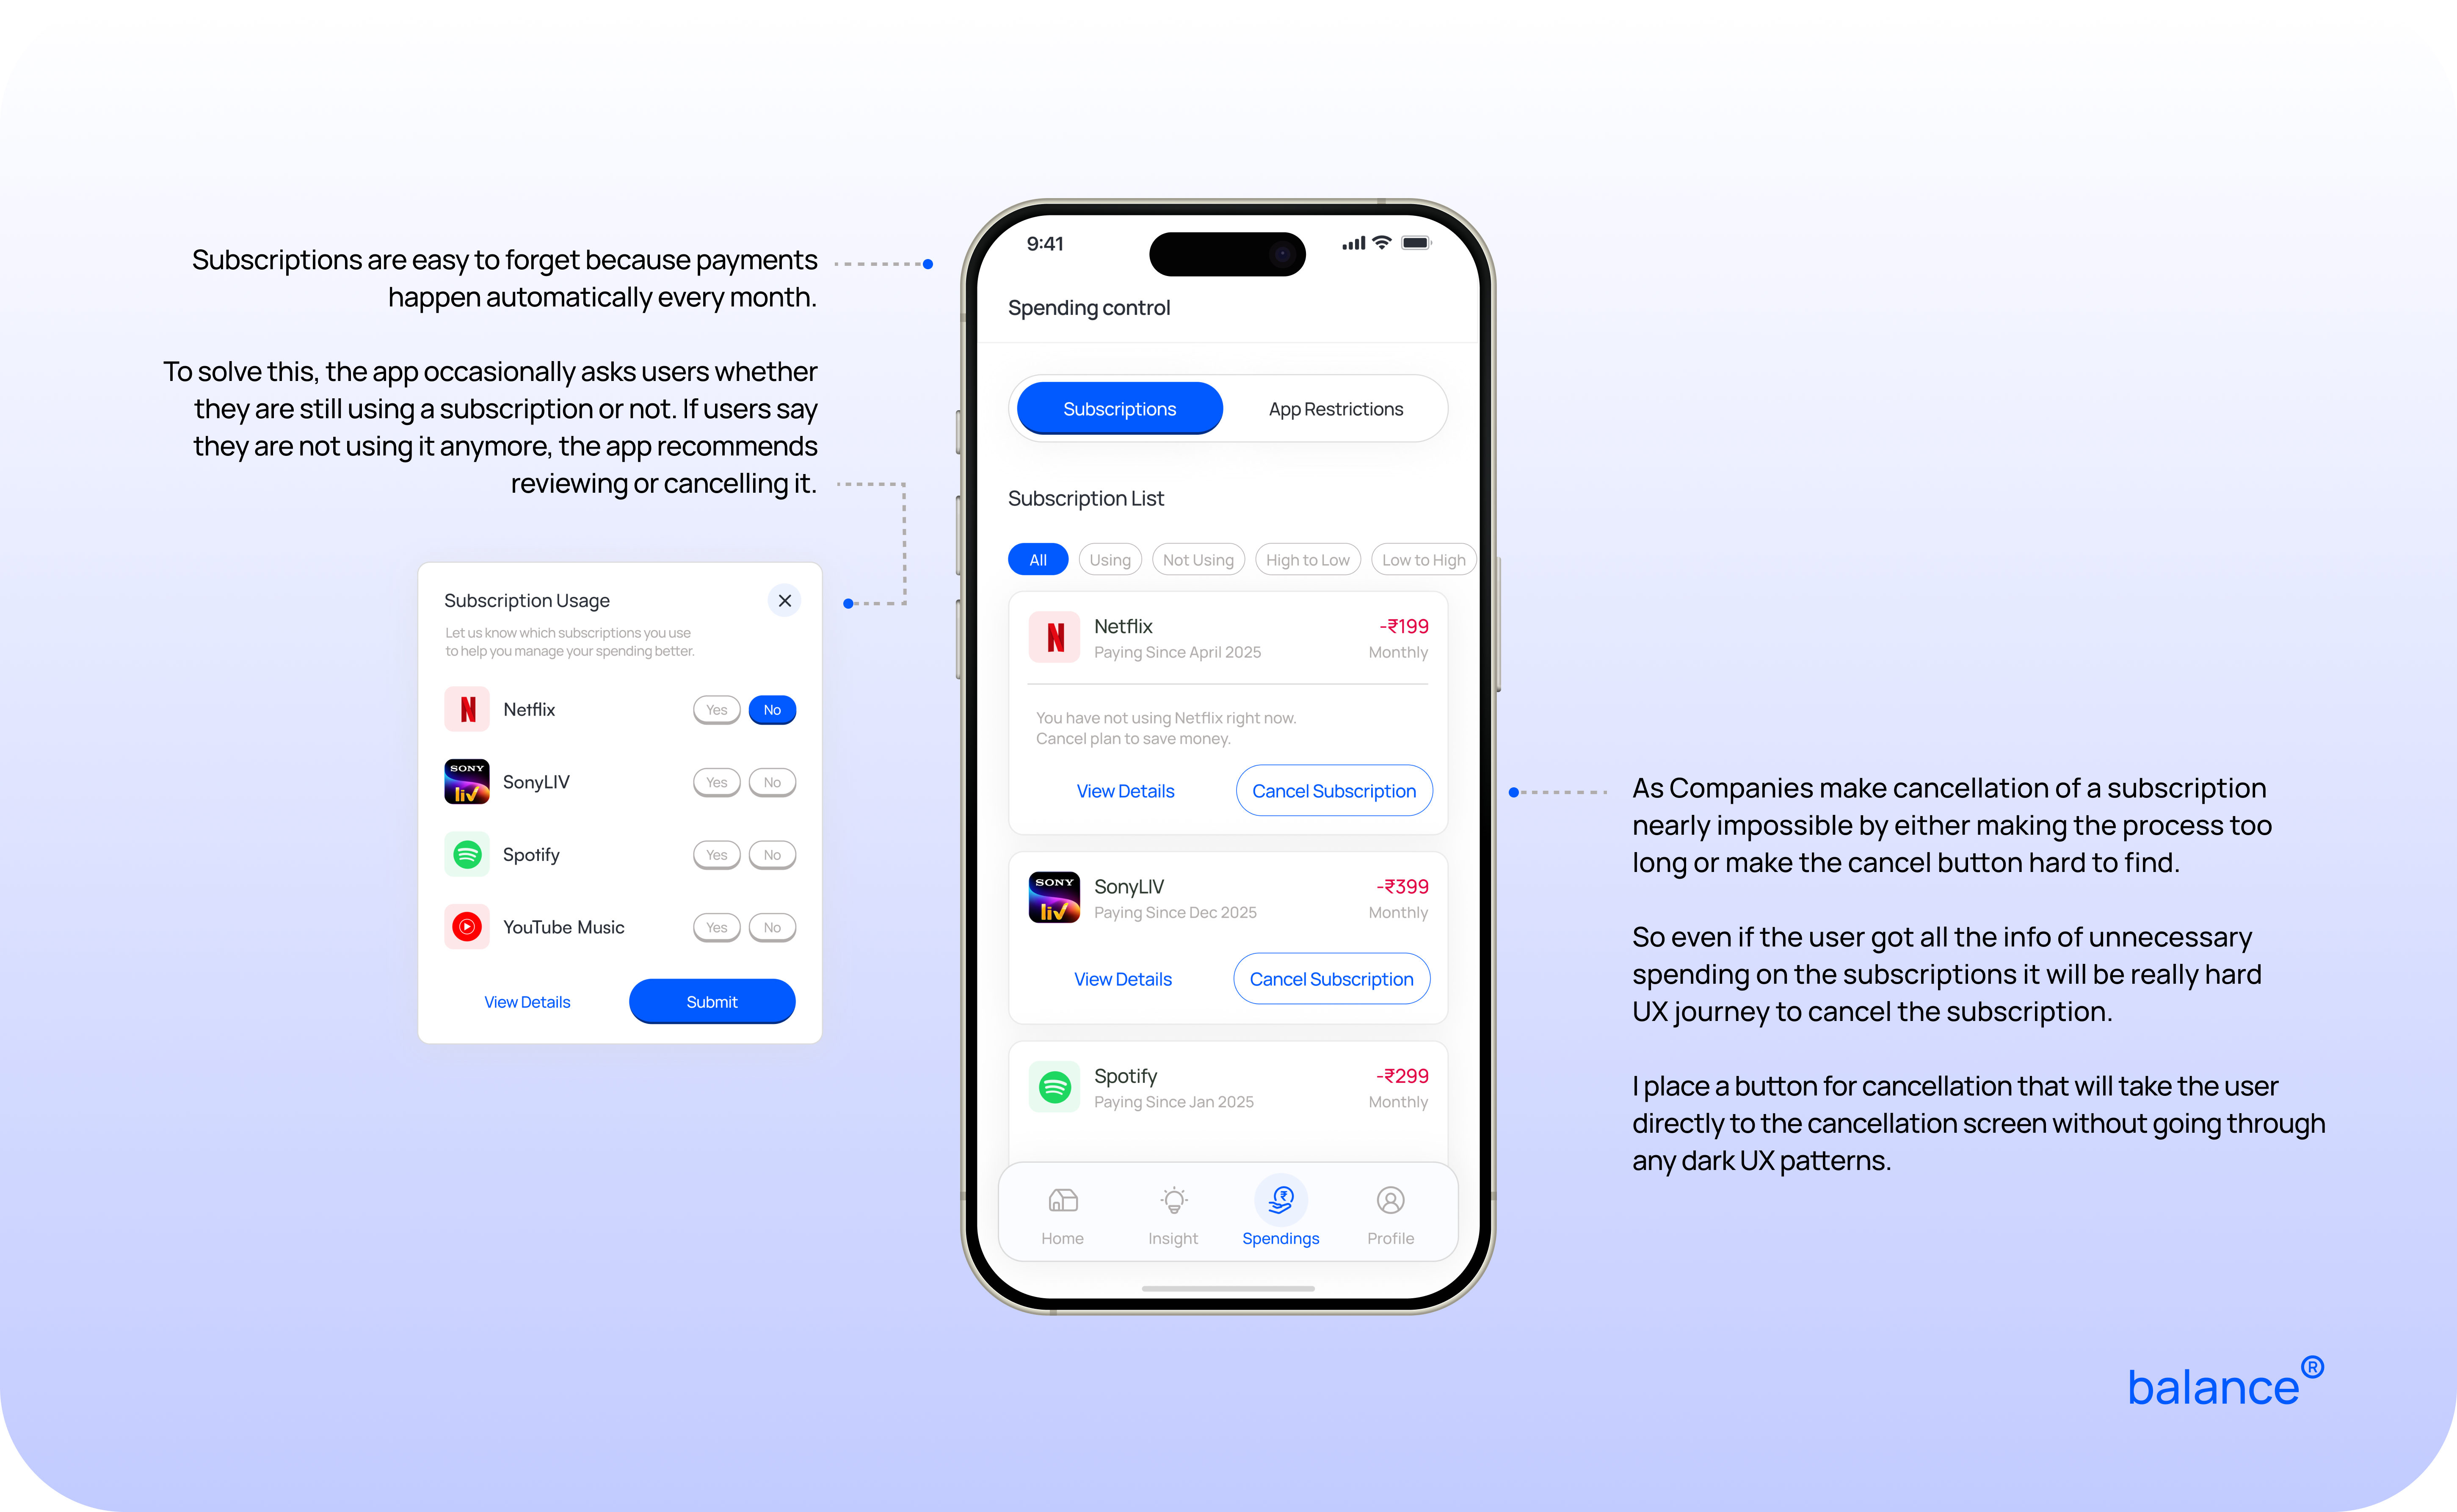
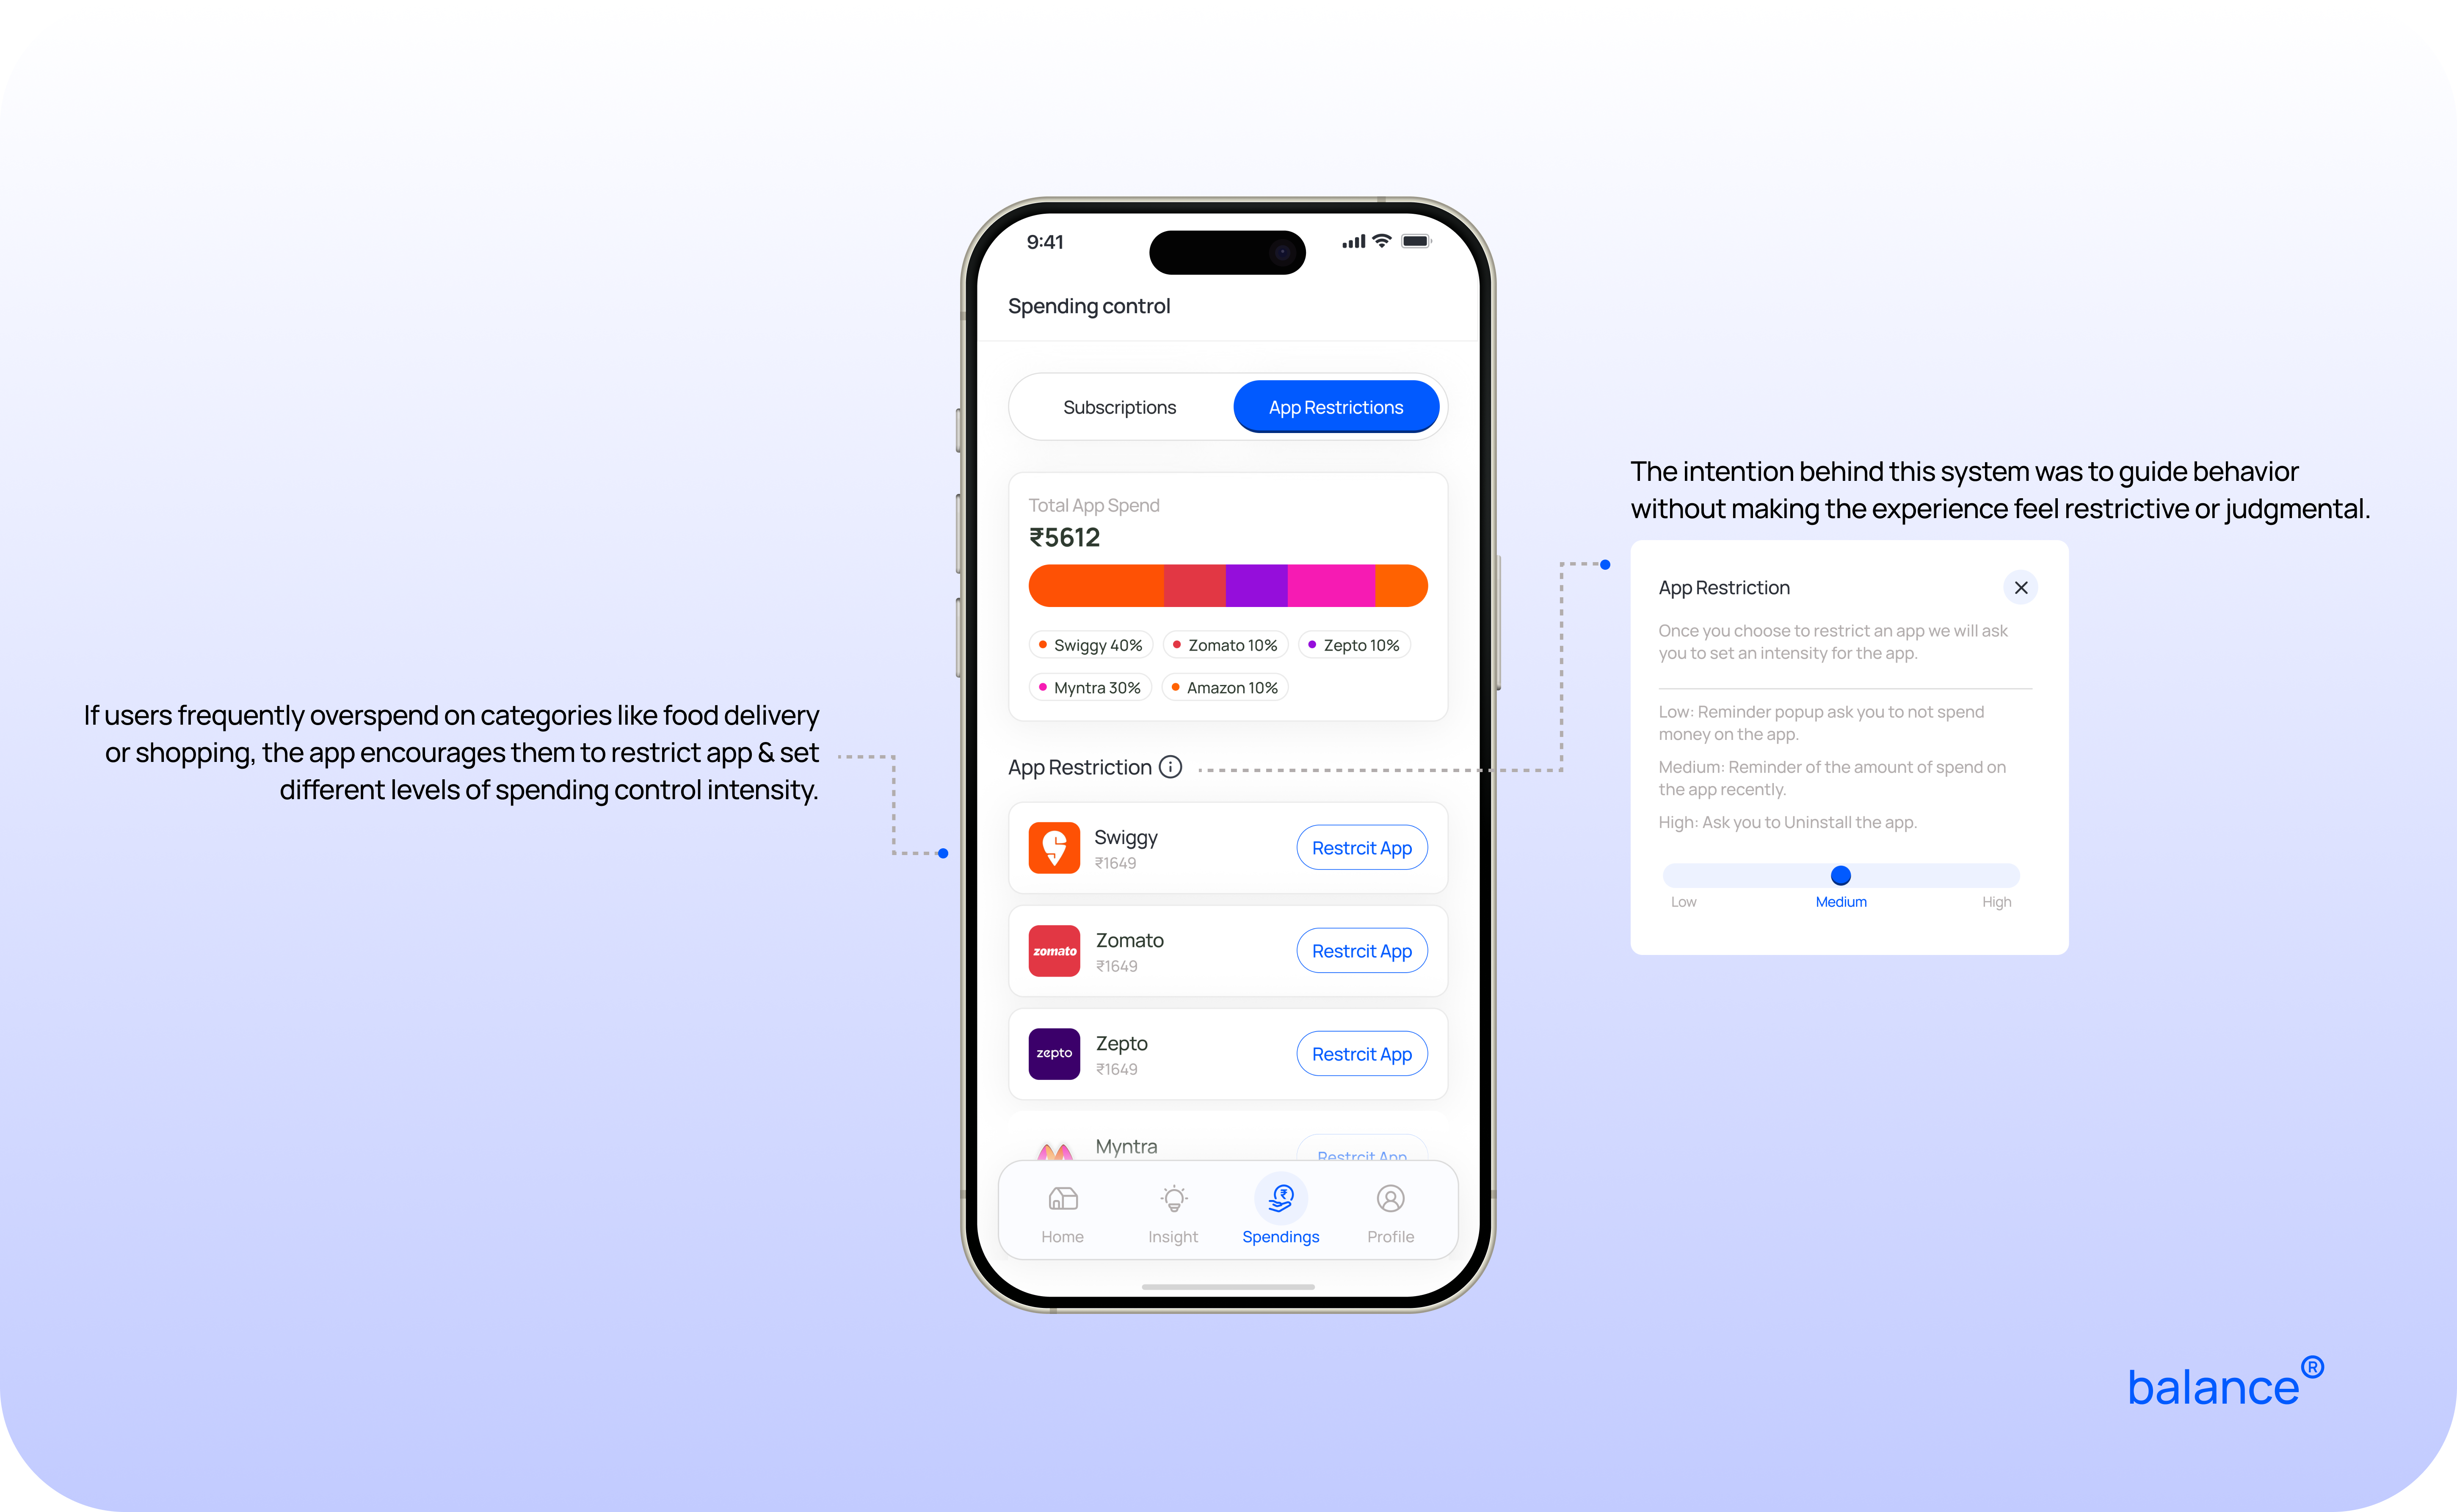
- Spending Control—This part helps users act on their spending habits. It focuses on subscription management and app-based controls where users can manage recurring expenses and choose different control levels for apps they overspend on.
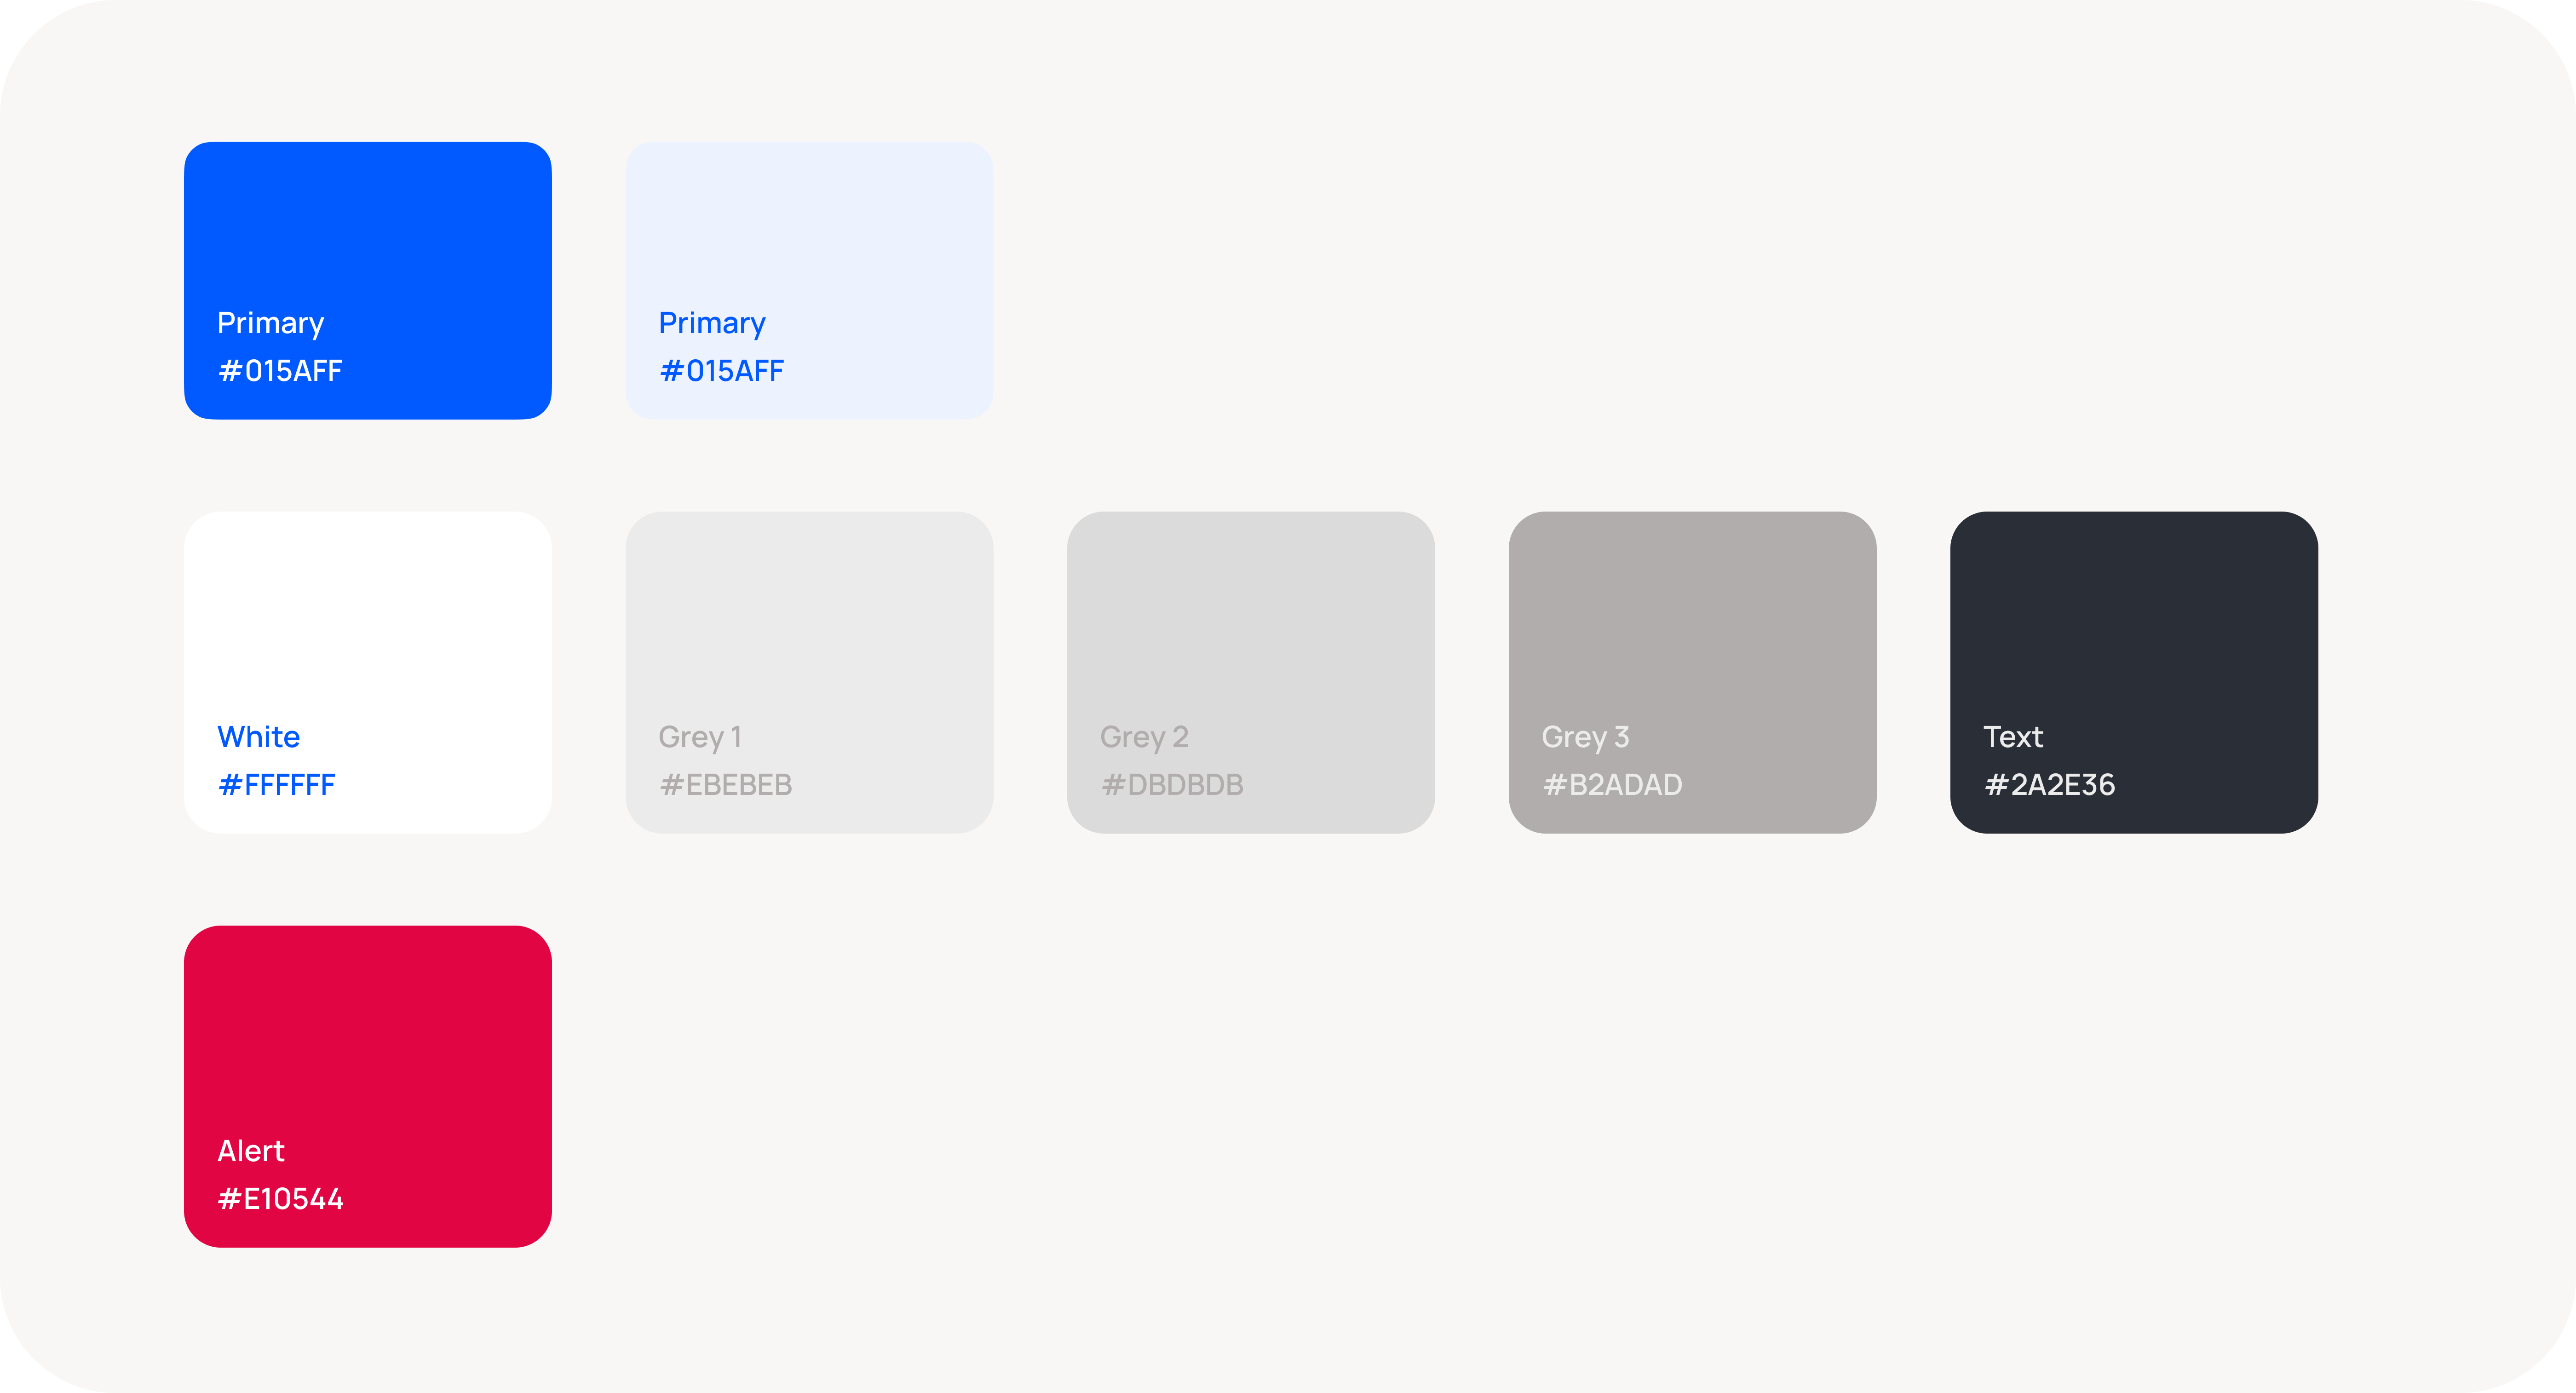
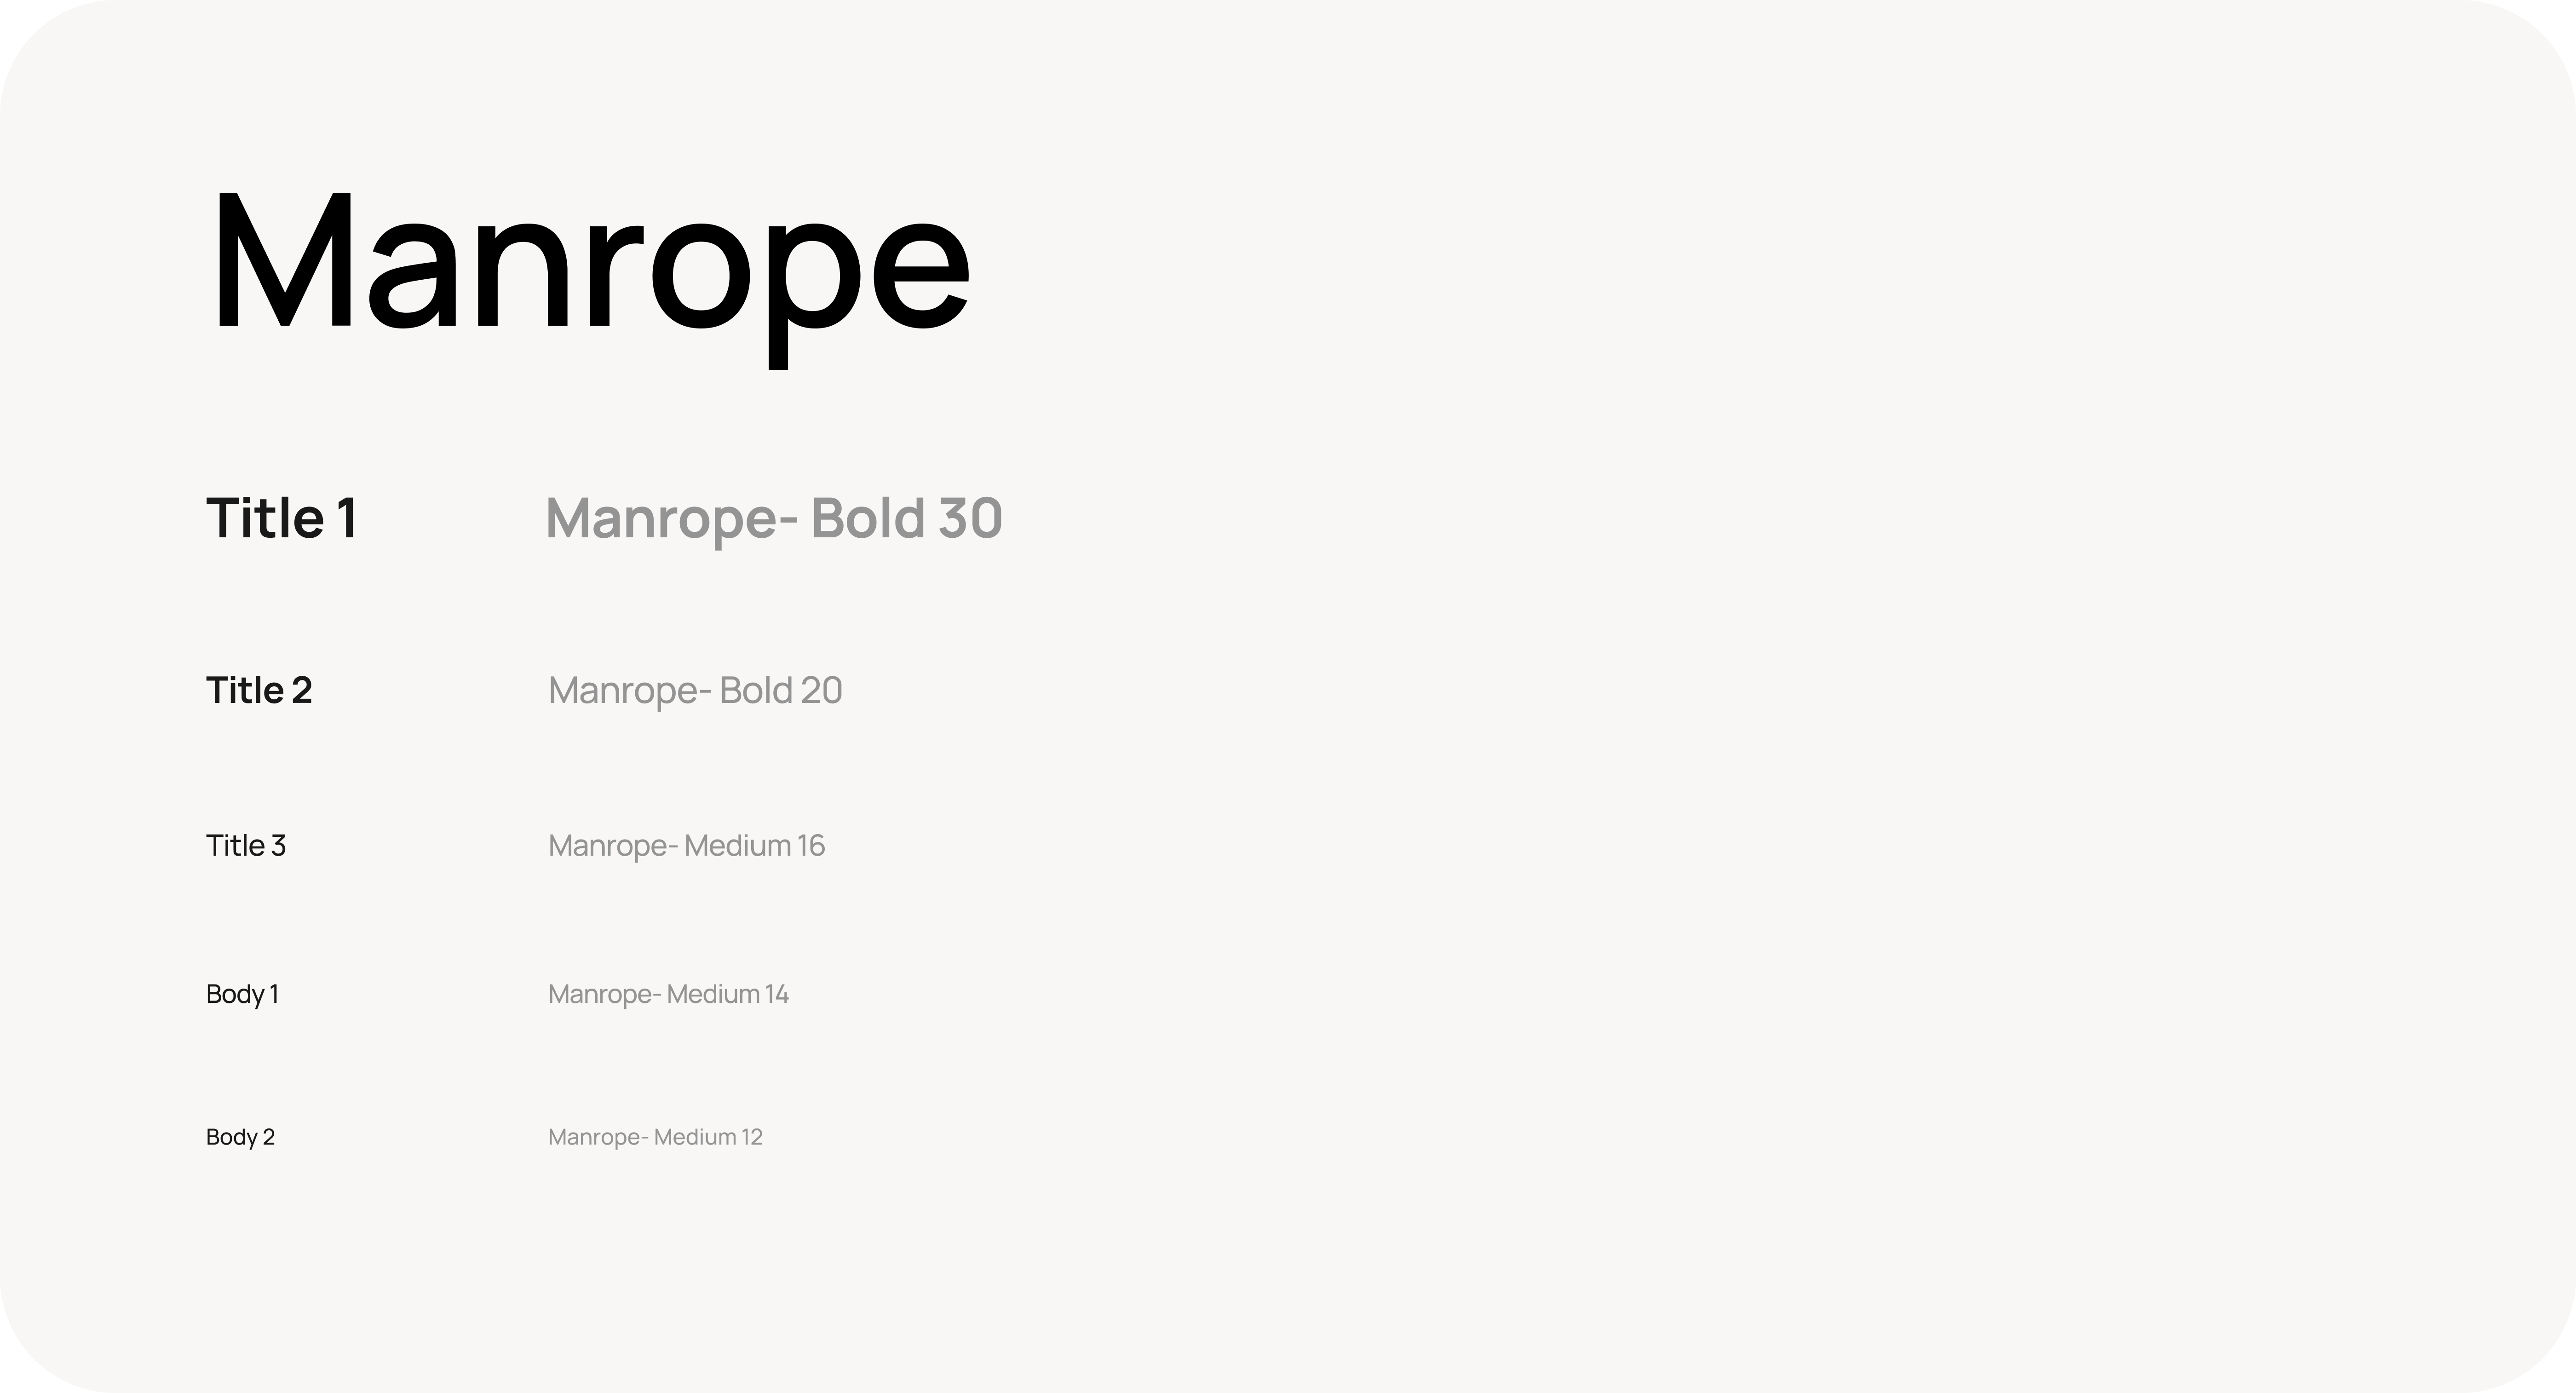
Constraints & Technical Limitations
Cancellation
- I initially explored allowing users to directly cancel subscriptions from inside the app. However, many platforms such as Netflix do not provide public APIs for third-party cancellation.
Instead of cancelling a subscription within the app, I placed a cancellation button that takes the user directly to the service’s cancellation screen without making them navigate through dark UX patterns.
Restrict Apps
- I also explored using app-usage data through Android Digital Wellbeing and iOS Screen Time APIs to detect whether users were actively using subscription services. However, this became unreliable when users consumed content through laptops and TVs.
Because of these limitations, I shifted toward a simpler and more transparent approach where users manually confirm through a modal whether they still use a subscription.
Cash In & Cash Out
While working on the transaction system for the home page, I realized that transactions still miss one important aspect—cash transactions.
One possible solution was to allow users to manually add cash expenses through a simple “Add” button whenever they spend cash. But this introduced another problem. If a user withdraws money from an ATM, that withdrawal already appears as an online transaction. Later, if the user manually adds an expense paid from that cash, it creates a double entry and makes the spending data inaccurate.
Users may also forget to log cash expenses. The app would then show lower spending than the user’s actual expenses, producing misleading insights and inaccurate financial graphs.
One approach I considered was treating cash withdrawals only as a note or record rather than a direct expense. This would prevent disruption to insights and graphs, but it still does not completely solve the problem of presenting clear and meaningful financial insights without confusing the user. Interestingly, Axio follows a similar approach for cash transactions.
Conclusion
This case study explored how a financial tracking app can become more guidance-driven instead of merely data-driven. The goal was to simplify financial management by helping users understand their spending behavior, control overspending, and build healthier financial habits through actionable insights and smart recommendations.
Throughout the process, I learned how small product decisions can significantly affect user trust, clarity, and the overall experience—especially in fintech products where accuracy and simplicity are equally important.